Underwriting has long been viewed as a strong candidate for automation because it is document-heavy, rule-driven, and repetitive. Despite years of investment in OCR, rules engines, and workflow tools, most underwriting teams still depend heavily on manual review.
The core reason is simple but critical: underwriting is not a single-document extraction task. It is a multi-document, context-rich, judgment-driven workflow. This distinction changes how automation must be designed, deployed, and trusted.
This article explains how modern underwriting automation actually works and why the convergence of advanced OCR, Large Language Models (LLMs), and Agentic AI is enabling true end-to-end automation, even for complex lines such as Inland Marine.
Automating Inland Marine Underwriting with OCR, LLMs & AI Agents
Effective underwriting automation requires combining OCR for text extraction, LLMs for reasoning and normalization, and Agentic AI for workflow execution.
Inland Marine underwriting involves diverse assets, inconsistent documents, and cross-document validation. No single technology can handle this alone. Only a coordinated system of OCR, LLMs, and AI agents can automate the process end to end.
The Reality: Not All PDFs Are Created Equal
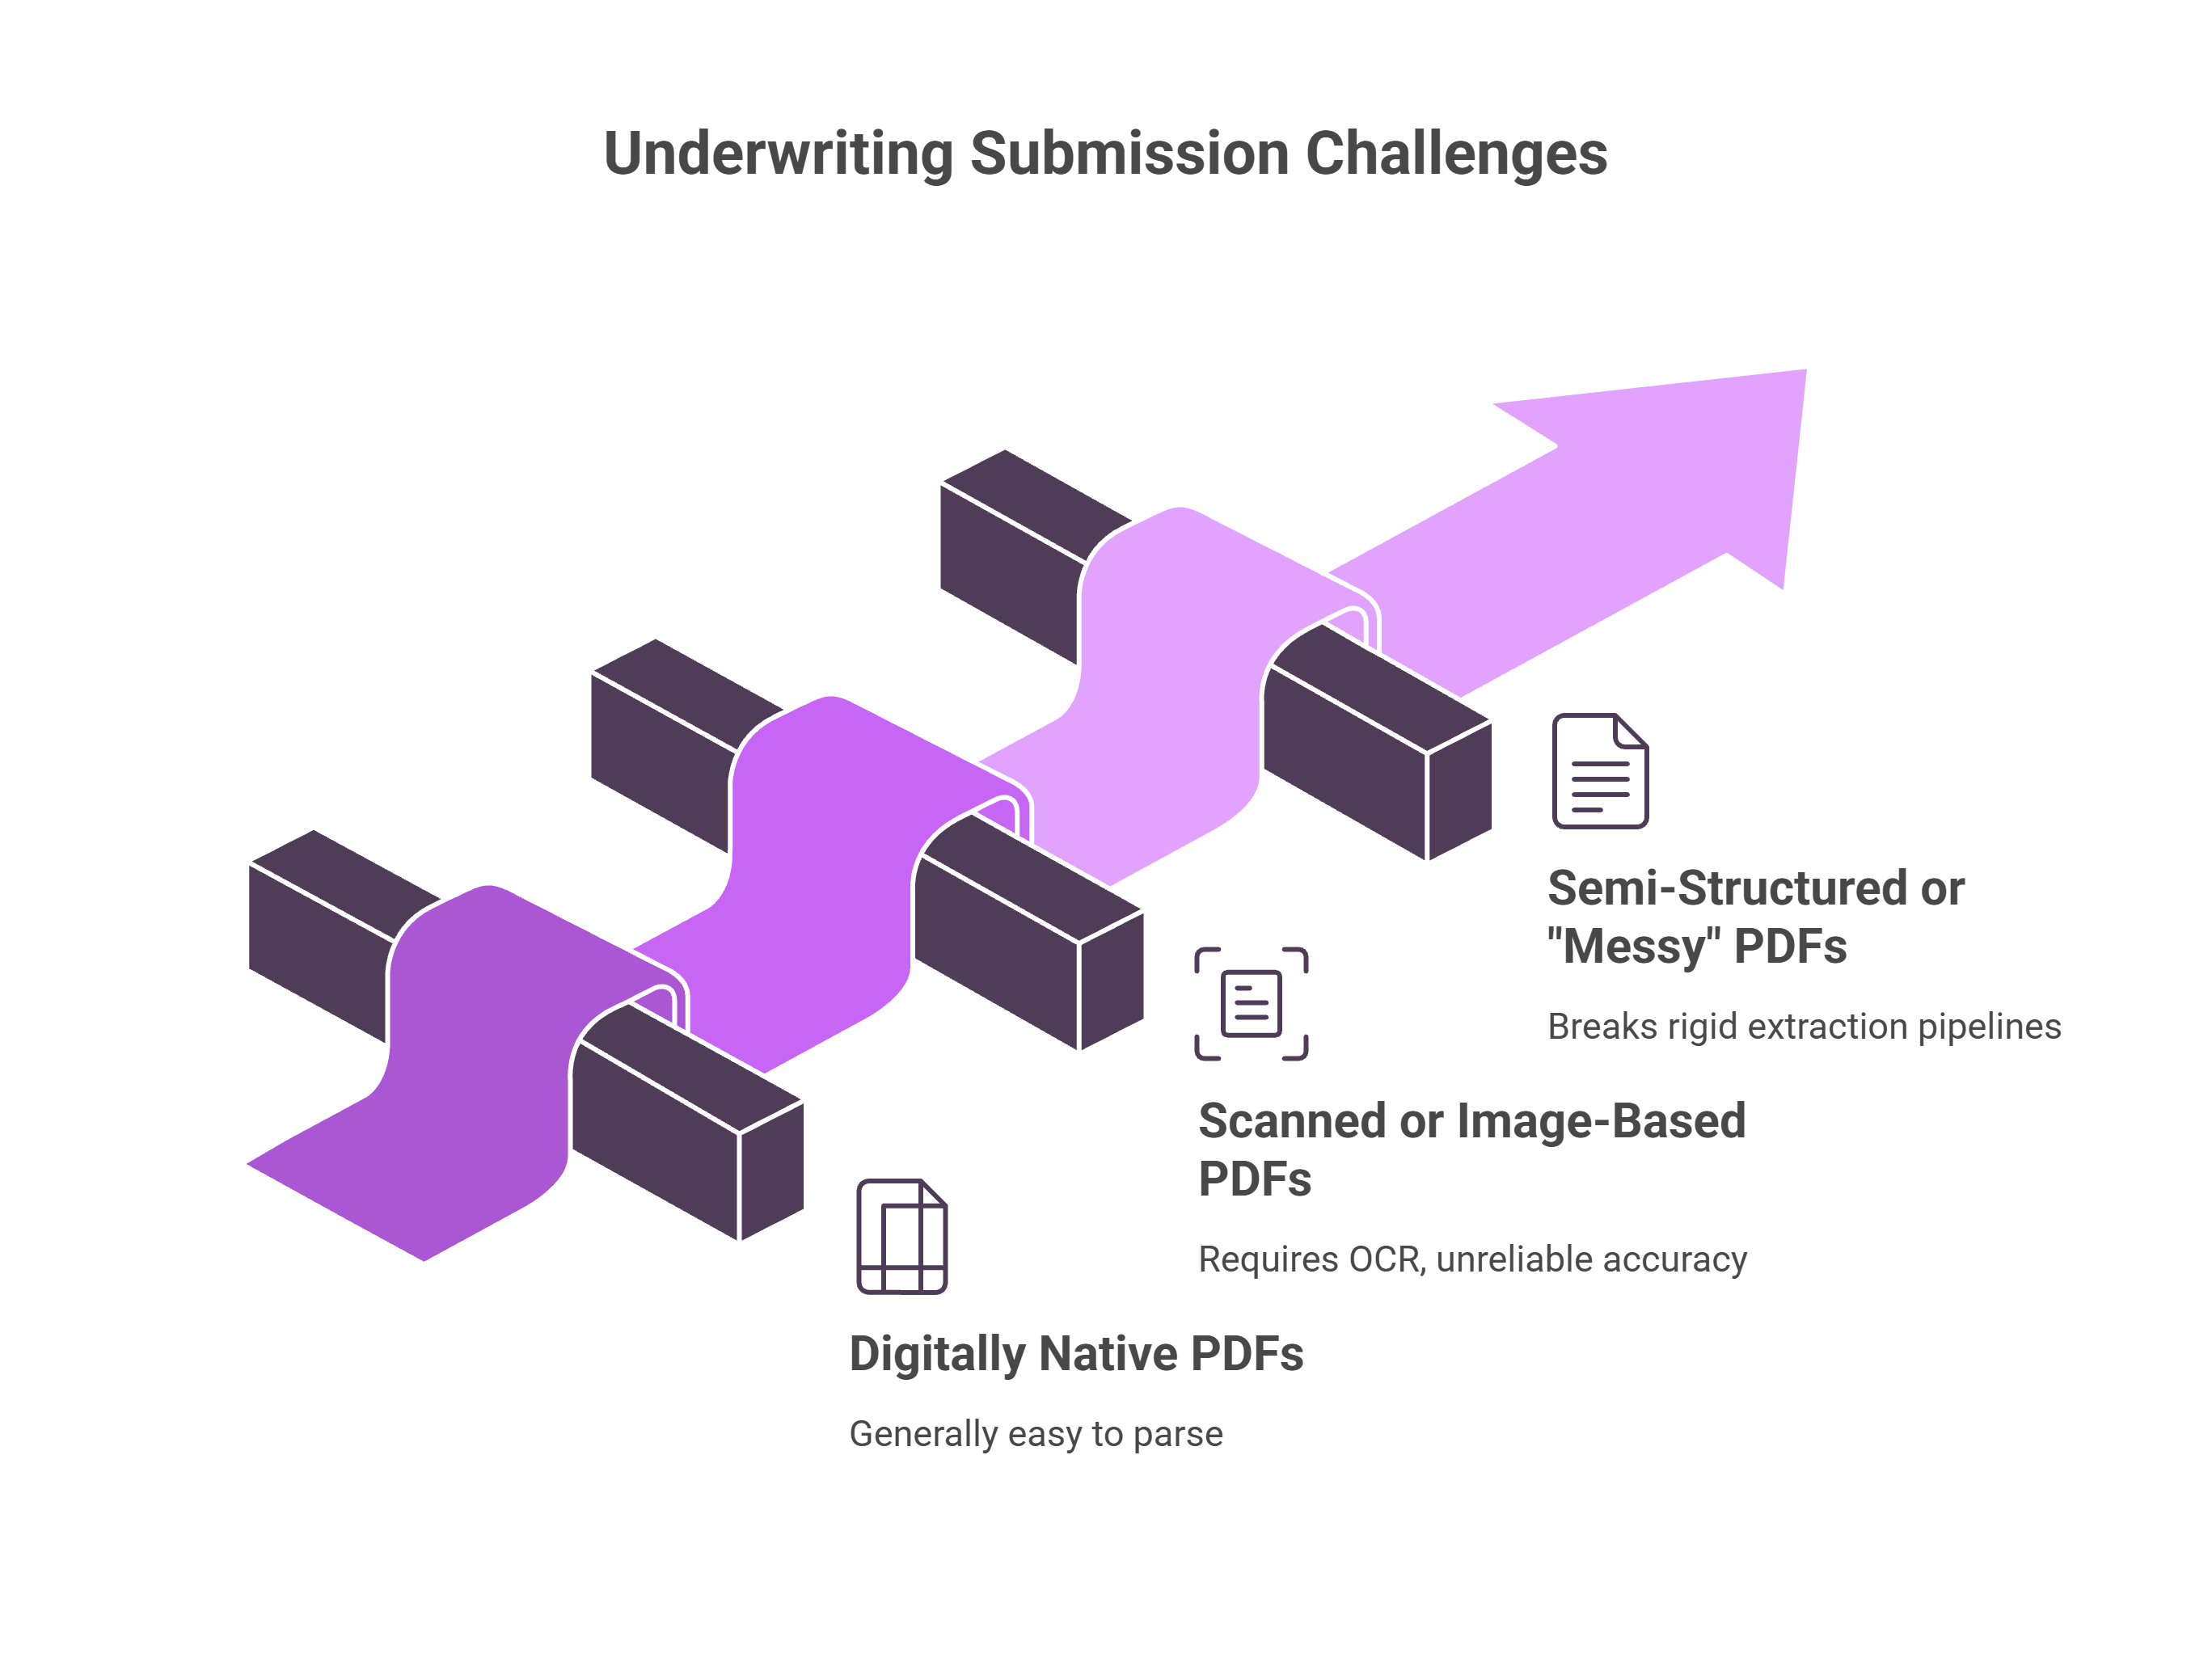
Underwriting submissions arrive in multiple document formats, each with different extraction challenges.
Underwriters must process a mix of digital, scanned, and semi-structured documents, often within the same submission.
1. Digitally Native PDFs
These include broker submissions, policy schedules, and coverage summaries generated by software systems. They usually contain selectable text, consistent tables, and predictable layouts. Traditional parsing tools work reasonably well for these files.
2. Scanned or Image-Based PDFs
Inspection reports, legacy schedules, handwritten notes, and stamped documents often fall into this category. These files contain only images and require OCR for text extraction. Accuracy and structural consistency are often unreliable.
3. Semi-Structured or “Messy” PDFs
These documents combine scanned and digital pages, use multi-column layouts, embed appendices mid-document, or split tables across pages. Such formats frequently break rigid extraction pipelines.
Real-world underwriting workflows almost always involve all three document types simultaneously. This is why single-point automation solutions consistently fail.
Why OCR Alone Is Not Enough
OCR extracts text but does not understand risk, relevance, or underwriting context. OCR answers only one question: “What characters appear on this page?” Underwriting requires deeper reasoning, including:
- Determining whether a value is relevant to a specific risk
- Identifying missing, contradictory, or implausible information
- Validating consistency across multiple documents
- Evaluating whether exposure justifies coverage limits
- Assessing acceptability for a specific line of business
Example: OCR can extract the text “Construction: Frame.” It cannot determine whether frame construction is acceptable for a specific Inland Marine exposure or whether factors such as protection class, location, or asset usage materially change the risk profile.
This limitation defines the functional ceiling of OCR.
The Role of LLMs in Underwriting Automation
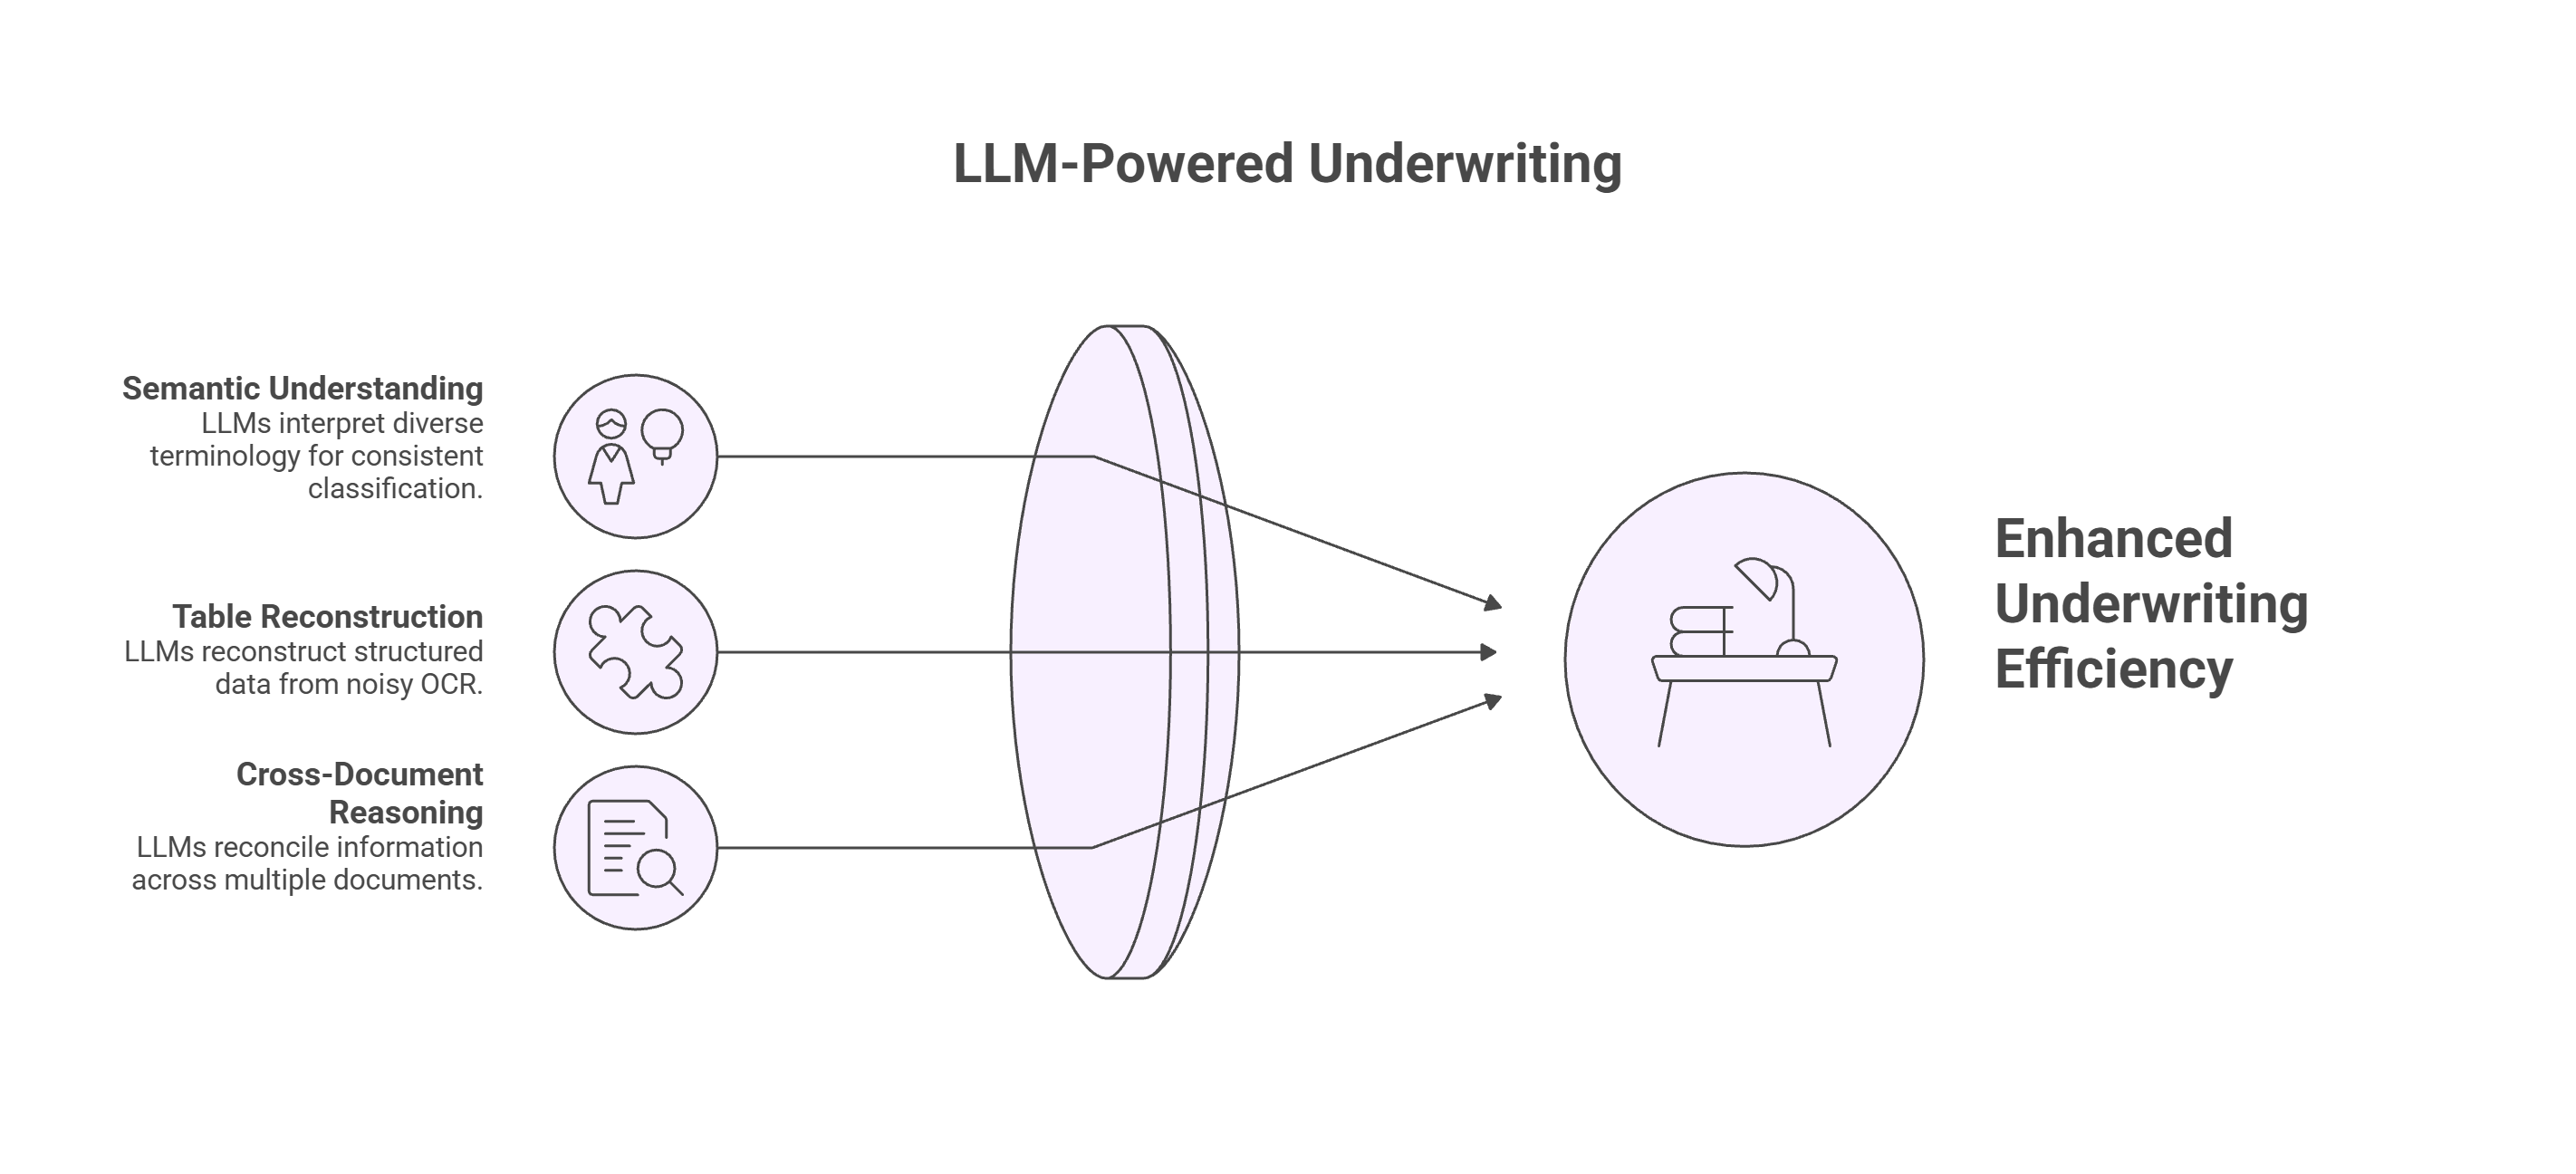
LLMs add semantic understanding, normalization, and cross-document reasoning to underwriting automation.LLMs are not used as conversational tools in underwriting. Their value lies in structured reasoning across complex document sets.
1. Semantic Understanding and Normalization
LLMs interpret inconsistent terminology across documents. For example, terms such as “steel shed,” “metal structure,” and “prefab unit” can be normalized into a unified construction classification. Coverage descriptions are understood contextually rather than through rigid keyword rules.
2. Table Reconstruction and Validation
LLMs reconstruct structured data such as Schedules of Values (SOVs) and COPE tables from noisy OCR output. Even when extraction is imperfect, headers, units, and field relationships are preserved.
3. Cross-Document Reasoning
LLMs reconcile information across the full underwriting packet, including:
- Submission details versus schedules
- Coverages versus exclusions
- Limits versus Total Insured Value (TIV)
LLMs reason holistically rather than document by document. They do not make final underwriting decisions. Instead, they surface inconsistencies, gaps, and risk signals for underwriter review.
Why Agentic AI Changes the Game
Agentic AI enables underwriting automation as a governed, auditable workflow rather than a single prompt.Underwriting is a process, not a query. Agentic AI systems break the workflow into deterministic, observable steps, including:
- Identifying and classifying document types
- Routing documents to native parsers or OCR engines
- Validating required fields and schemas
- Applying risk scoring and business logic
- Flagging exceptions and missing information
- Generating underwriting summaries and quote-ready outputs
Each step is repeatable and explainable, which is essential in regulated environments where trust and control are mandatory.
Automating Inland Marine Underwriting with OCR, LLMs & AI Agents
Why Inland Marine Is the Ultimate Stress Test
Inland Marine underwriting tests the full limits of automation due to its complexity and variability.This line of business involves:
- Highly diverse asset types
- Significant location variability
- Exposure-based pricing models
- A high frequency of non-standard risks
If an AI system can automate Inland Marine underwriting end to end, it demonstrates the capability to handle most specialty insurance lines. For this reason, Inland Marine serves as a proving ground for agentic underwriting systems.
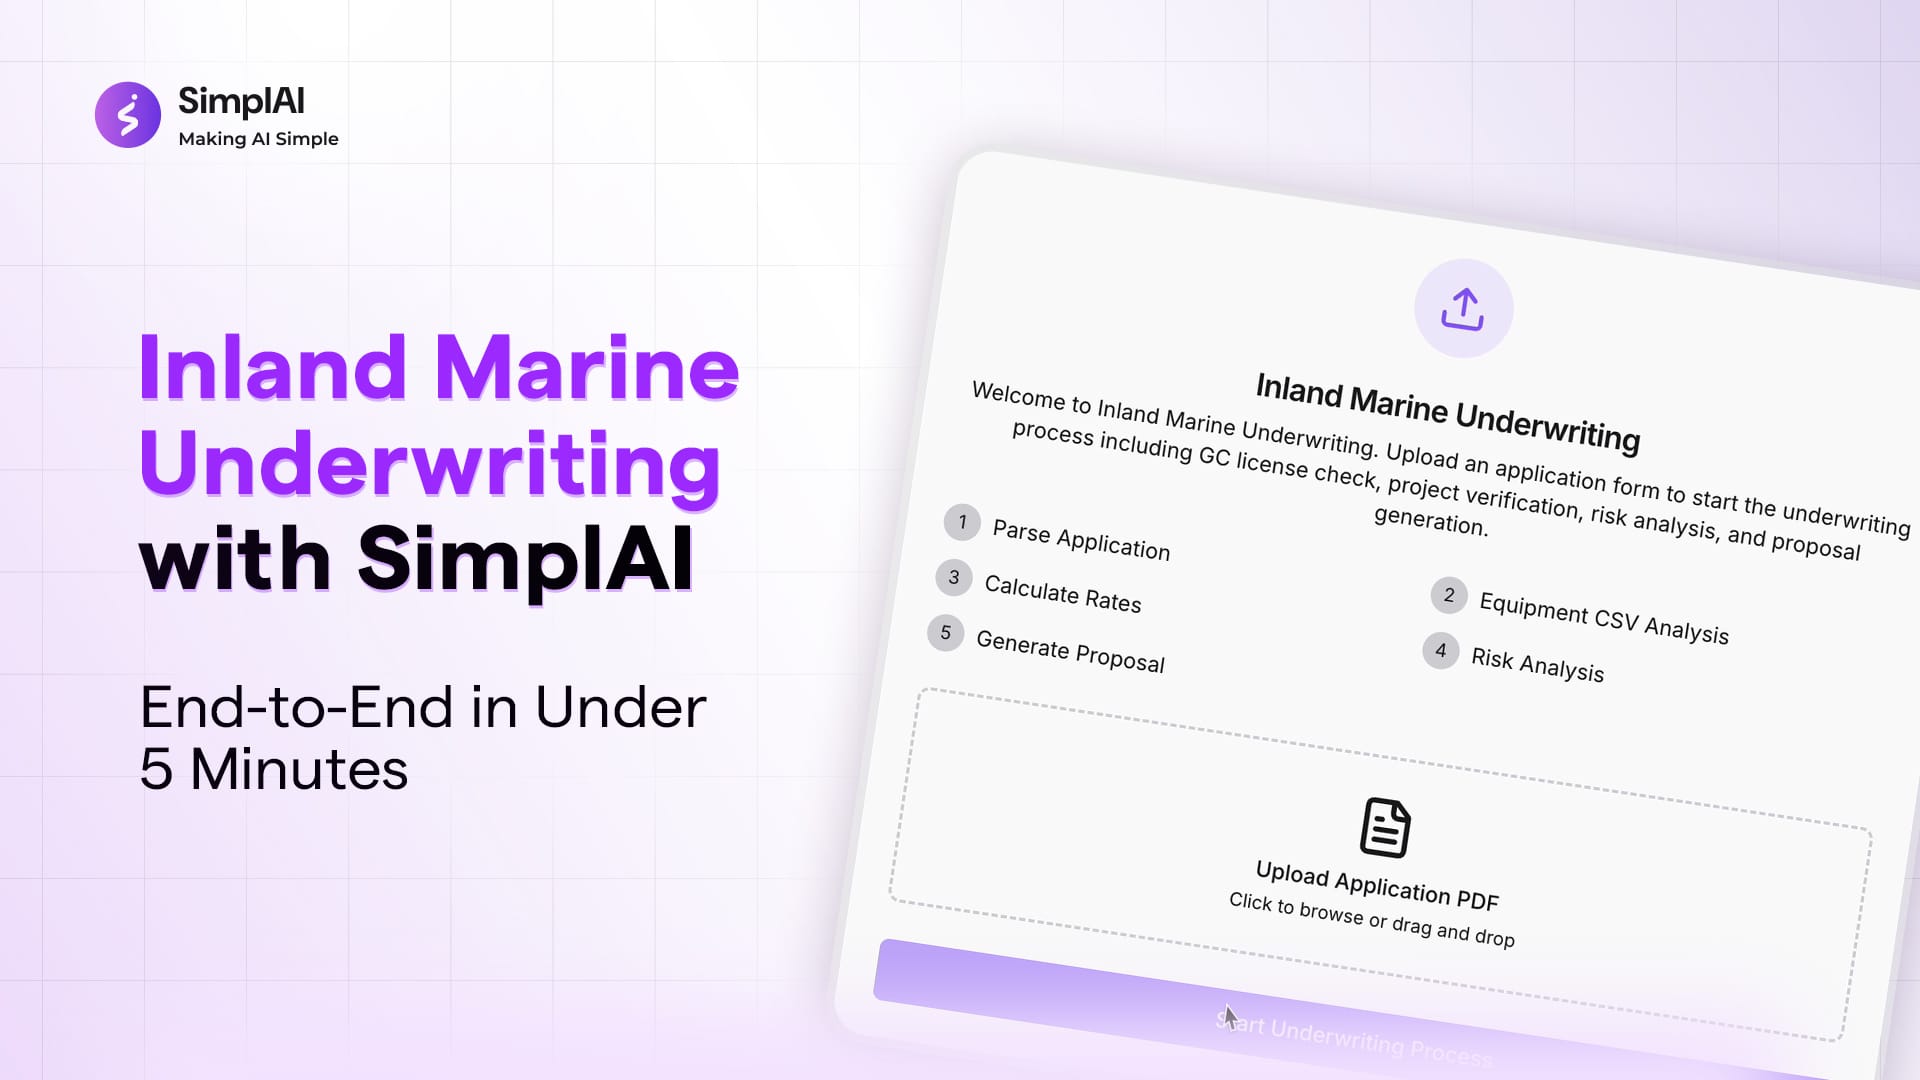
See how an end-to-end agentic underwriting system automates document ingestion, cross-document validation, risk analysis, and exception handling for Inland Marine insurance.
The Bigger Shift: From Tools to Systems
The future of underwriting automation lies in systems, not isolated tools.Automation does not fail because OCR or LLMs lack accuracy. It fails when workflows are not modeled correctly.
The next generation of underwriting platforms combines robust OCR, LLM-driven reasoning, and agentic execution into governed systems designed to mirror how expert underwriters work. This shift from tools to systems is already underway.
Frequently Asked Questions
Why doesn’t OCR alone automate underwriting?
OCR extracts text but cannot evaluate relevance, consistency, or risk. Underwriting requires contextual reasoning across multiple documents.
How do LLMs improve underwriting automation?
LLMs normalize terminology, reconstruct complex tables, and reconcile information across documents to surface inconsistencies and risk signals.
Do LLMs make underwriting decisions?
No. LLMs assist by highlighting gaps, contradictions, and insights, but final decisions remain with underwriters.
What makes Agentic AI different from prompt-based automation?
Agentic AI breaks underwriting into governed, auditable steps instead of handling everything through a single prompt.
Why is Inland Marine underwriting so difficult to automate?
It involves diverse assets, variable locations, exposure-based pricing, and non-standard risks, making it a strong test case for automation systems.
Author bio