Why SimplAI is the critical infrastructure layer that enterprises, partners, and the broader AI ecosystem cannot afford to ignore
Contents
- Executive Abstract — The Governance Crisis
- The Six Pillars of Enterprise AI Readiness
- Why Hyperscalers Cannot Solve the Problem
- Why Model-Only Companies Fall Short
- Why Open-Source Frameworks Are Not the Answer
- SimplAI’s Irreplaceable Value for Partners
- SimplAI in the Broader AI Ecosystem
- Conclusion — The OS Imperative
Executive Abstract
The Governance Crisis Hiding Inside Every Enterprise AI Budget
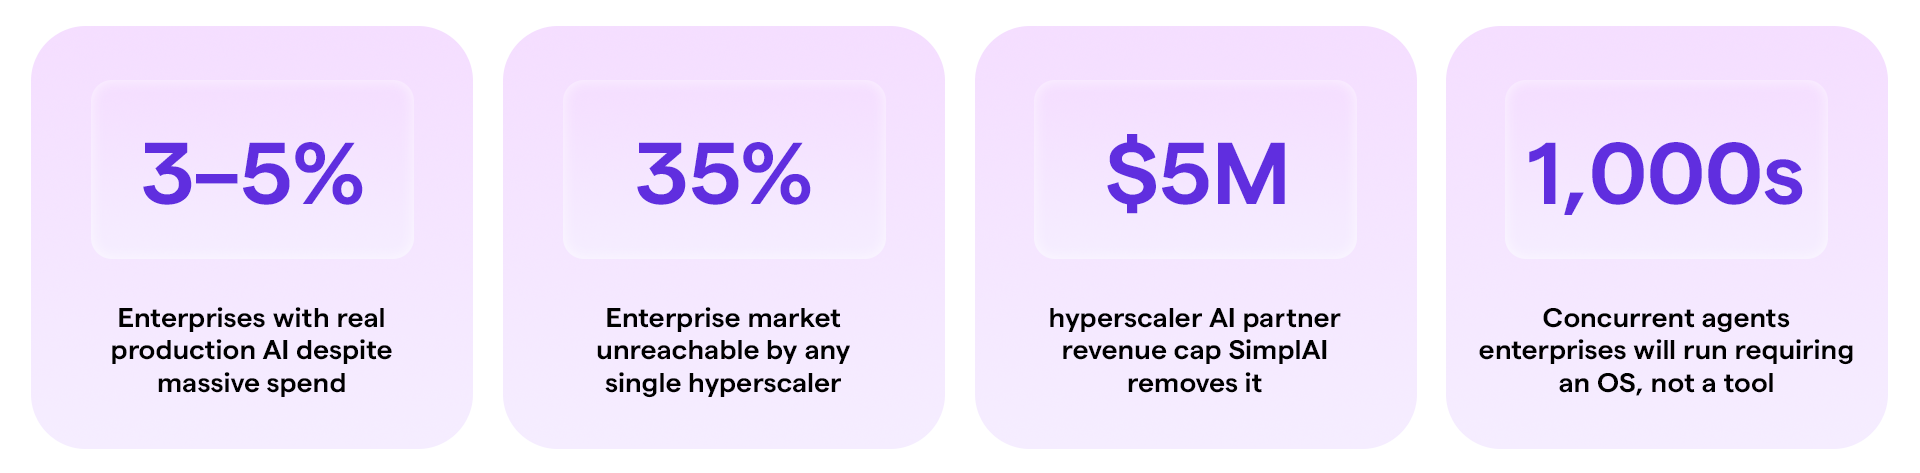
Enterprises across every sector have spent the last two and a half years making enormous bets on artificial intelligence. They have procured GPU clusters, signed multi-million dollar commitments with hyperscalers like AWS, Azure, and GCP, licensed frontier models from Anthropic, OpenAI, and Google, and distributed dozens of point-solution tools — Cursor, GitHub Copilot, Windsurf — across their developer organizations. On paper, these organizations are heavily invested in AI. In practice, fewer than 3 to 5% of them have achieved meaningful, production-scale adoption.
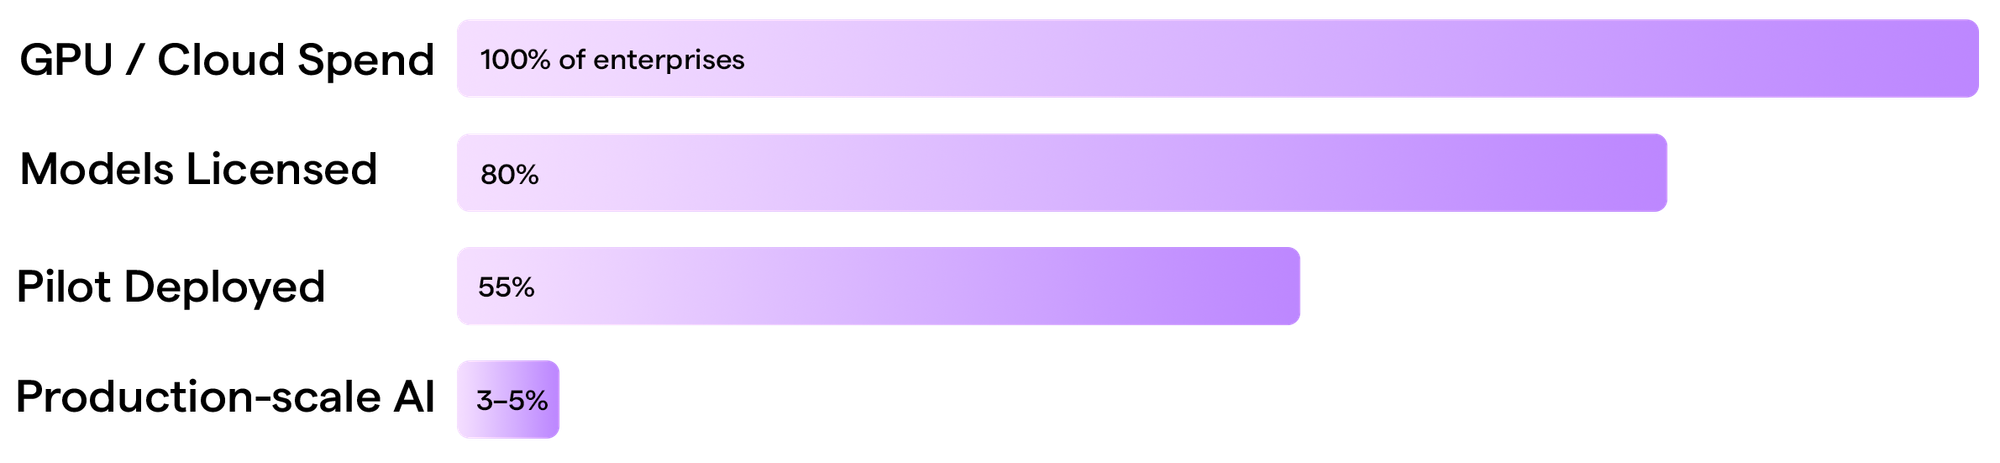
The reason is not capability. The models are capable. The cloud infrastructure exists. The reason is the complete absence of an operating layer — a unified system that provides orchestration, security, compliance, governance, scalability, and field deployment engineering in a single, cloud-agnostic, model-agnostic platform.
This is precisely the void that SimplAI fills. SimplAI is not a model. It is not a cloud. It is not a framework. It is the enterprise operating system for the agentic era — the connective tissue that ties together every investment an organization has already made and transforms scattered AI spending into a coherent, governed, scalable strategy.
“You cannot adopt AI in enterprises unless you have the operating system approach — where orchestration, contextualization, model agnosticism, cloud agnosticism, compliance, and governance are all together, working at scale.”
Core Architecture
The Six Pillars of Enterprise AI Readiness
SimplAI value proposition is constructed on six foundational pillars. Each pillar represents a dimension where enterprises currently face critical gaps — and where SimplAI delivers production-grade capabilities that no single hyperscaler, model provider, or open-source framework can replicate.
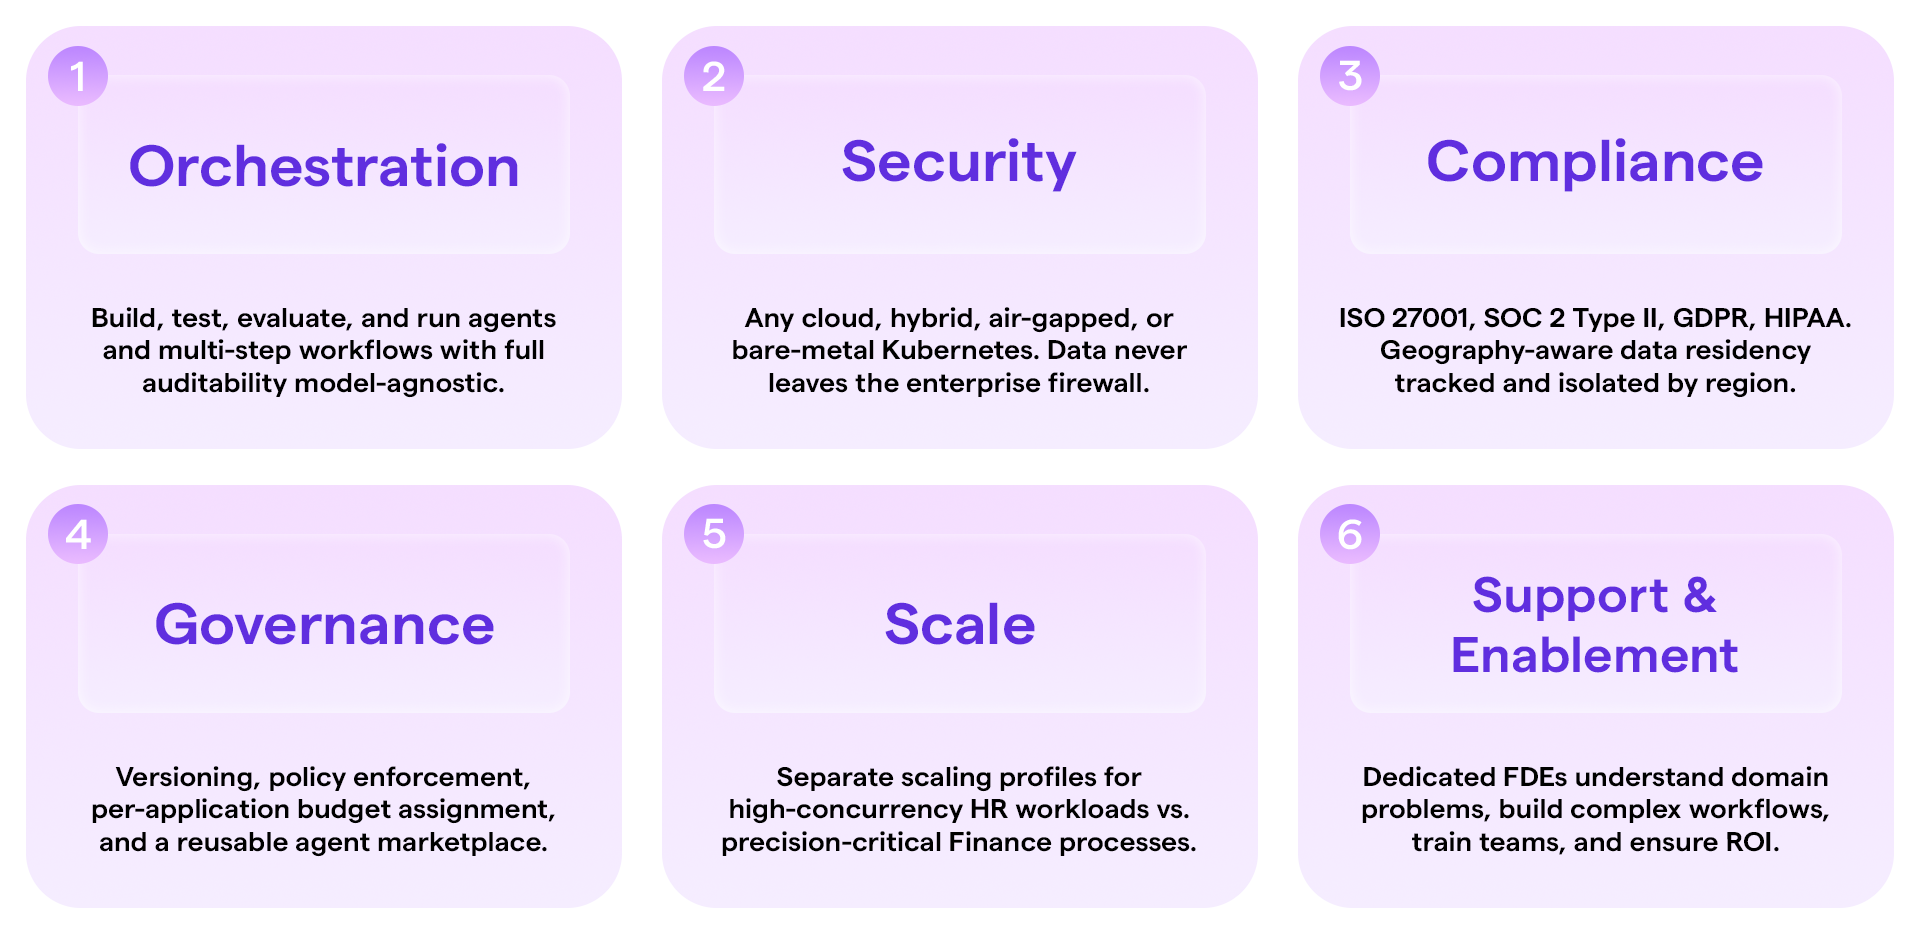
The crucial insight is that these six pillars are interdependent. A solution that delivers orchestration without governance creates uncontrolled token spend. Security without compliance fails regulatory audits. Scalability without field deployment engineering leaves enterprises unable to operate the platform. SimplAI is the only platform that integrates all six into a unified operating system, purpose-built for enterprises running thousands of concurrent agents across heterogeneous environments.
The 80/20 enterprise architecture: 80% is the operating system — orchestration, compliance, governance, security, scale, and deployment. Only 20% is customization. This ratio inverts the traditional build-everything approach and is why SimplAI-powered enterprises reach production 10x faster than those building on frameworks alone.
Competitive Landscape
Why Hyperscalers Cannot Be the Answer
The most natural objection enterprises raise is: “Why not just build on Vertex AI, AWS Bedrock, or Azure AI Foundry?” This objection deserves a direct, structured answer. Hyperscalers are extraordinary infrastructure providers. They are not enterprise AI operating systems.
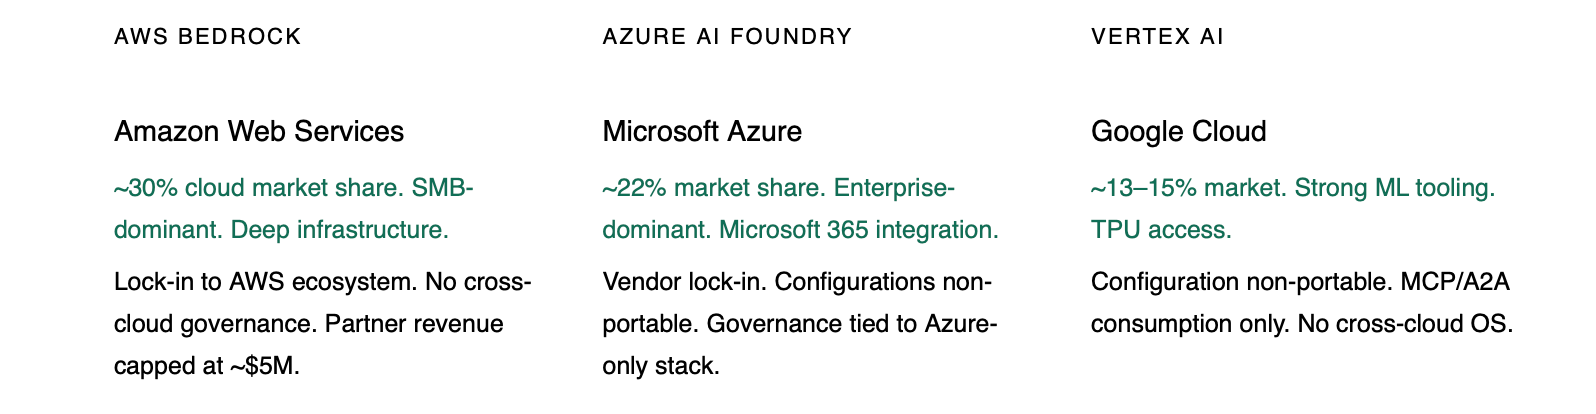
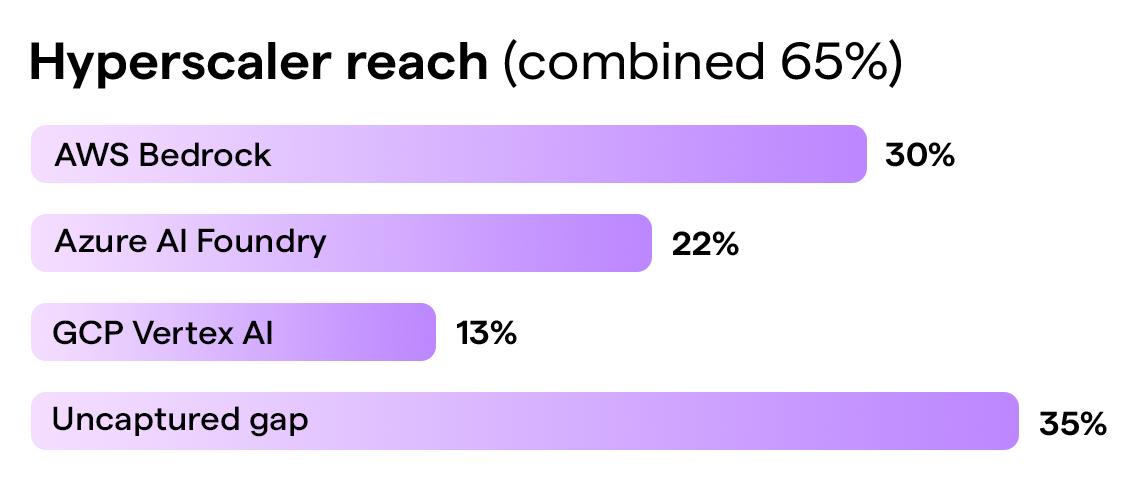
Together, AWS, Azure, and GCP control approximately 65% of the cloud market. But three fundamental constraints make hyperscaler-native AI platforms inadequate for enterprise operating-system needs:
First, interoperability
A workflow built on Vertex AI cannot be portably deployed to Azure. The three configuration layers — agent/tool configuration, runtime dependencies, and infrastructure — are each tightly bound to the hyperscaler’s proprietary stack. SimplAI operates above all three layers, making deployments genuinely portable.
Second, the 35% gap
Even if an enterprise optimizes perfectly across all three major hyperscalers, they address only 65% of the market. Sovereign clouds, private data centers, air-gapped environments, and emerging regional cloud providers represent 35% of enterprise deployments that hyperscaler-native tools simply cannot reach. SimplAI is present everywhere.
Third, partner economics
Hyperscalers typically cap their top-tier AI partner programs at approximately $5 million in annual revenue potential. SimplAI removes this ceiling entirely. Partners who build their practice on SimplAI can address 100% of market — across all clouds, all sovereign environments, all industries — with no artificial revenue cap and significantly higher margins from the SI business component.
SimplAI is not competing with hyperscalers. It is co-selling through their marketplaces. When an enterprise uses SimplAI on GCP, their GCP commitment spend is satisfied — solving the CFO’s budget problem without requiring new budget carve-outs.
Model Provider Analysis
Why Model-Only Companies Cannot Govern What They Power
The second competitive objection is subtler and more ideologically charged: “The model will do everything. We just need Anthropic, OpenAI, or Gemini.” This belief is widespread — and demonstrably wrong. Not because the models are insufficient, but because governance, compliance, and scale are not problems that intelligence can solve by itself.
Consider what model providers cannot give enterprises: they cannot provide cross-model governance when an enterprise is simultaneously using Claude, GPT-4o, Gemini, Mistral, and Grok for different workloads. They cannot prevent runtime artifact generation from producing uncontrolled token explosions. They cannot give enterprises predictable cost envelopes across heterogeneous deployments. They cannot enforce data residency requirements that differ across geographic jurisdictions.
“A CIO of a company with 3,000 engineers — all using Cursor powered by Claude — suddenly found every developer locked out of their sessions. The token budget had burst without warning. $600 million in yearly IT budget, and nobody had planned for this. The entire organization ground to a halt.”
— Sandeep Dinodiya, SimplAI, from direct enterprise field experience
This is not an edge case. It is the predictable outcome of deploying intelligent systems without an intelligent governance layer. Token consumption is opaque when model providers control the pricing surface. Models generate runtime artifacts — code, structured outputs, intermediate reasoning traces — that multiply token usage in ways that are invisible to procurement and finance teams until the invoice arrives.
Furthermore, enterprises are deeply reluctant to create single-model dependencies. Every enterprise that has committed to one model provider understands the existential risk: if that model degrades, goes offline, changes pricing, or gets superseded, the entire business stack that depends on it is exposed. SimplAI’s model-agnostic architecture is not a feature — it is enterprise risk management.
The final point is commercial rather than technical. If an enterprise builds its AI infrastructure directly on a model provider, what does it share with customers? Its prompt structure? Its integration architecture? Its competitive differentiation evaporates. SimplAI provides the abstraction layer that allows enterprises to own their AI stack without owning the underlying intelligence — preserving proprietary advantage while benefiting from every model generation.
Importantly, model providers themselves understand this dynamic. Frontier labs like Anthropic, OpenAI, and Google are actively seeking operating-system partners like SimplAI because they know enterprise adoption cannot scale through direct model access alone. SimplAI accelerates model adoption — it does not compete with it.
Framework Analysis
Why Open-Source Frameworks Are Necessary but Not Sufficient
The open-source framework ecosystem — LangChain, LangGraph, LlamaIndex, CrewAI, AutoGen — has been extraordinarily valuable for accelerating AI experimentation. But the transition from framework-based experimentation to enterprise-grade production deployment exposes a chasm that frameworks were never designed to bridge.
Frameworks operate at a single layer of a three-layer architecture. The configuration layer — where agents, tools, and workflows are defined — is where frameworks shine. But two other layers are left entirely to the developer: the runtime dependency layer (API connectors, third-party services, custom integrations) and the infrastructure layer (where scaling actually happens). Enterprises that build production systems on frameworks alone discover this too late.
The operational consequences are severe. A production deployment requires tracing — so engineers add a tracing framework. Then it requires integration harnesses — so they add another. Then routing logic between agents — another dependency. Then monitoring, then compliance logging, then infrastructure autoscaling. Each additional framework creates a new maintenance surface, a new dependency on an open-source maintainer’s release cadence, and a new vector for breaking changes. Organizations end up stitching together ten or more frameworks and still lacking production-grade control.
The insurance claim scenario: Automating end-to-end claims processing — intake, validation, underwriting, approval, payment — requires orchestrating heterogeneous integrations, on-premises mainframe data, high concurrency at scale, and precise audit trails. No single framework addresses all of these. SimplAI does.
SimplAI does not replace frameworks — it transcends them. Internally, SimplAI’s agentic framework handles orchestration. But it exposes this through a unified operating system that also addresses runtime dependencies and infrastructure scaling, while providing the governance, compliance, and observability layers that frameworks never even attempted to solve. The result: teams that previously needed ten frameworks need one platform.
Partner Economics
SimplAI as a Category-Defining Partner Opportunity
For system integrators, cloud-native consultancies, and technology partners, SimplAI represents one of the most structurally attractive go-to-market opportunities in the current enterprise technology cycle. The reasons are both economic and strategic.
Total addressable market without artificial ceilings
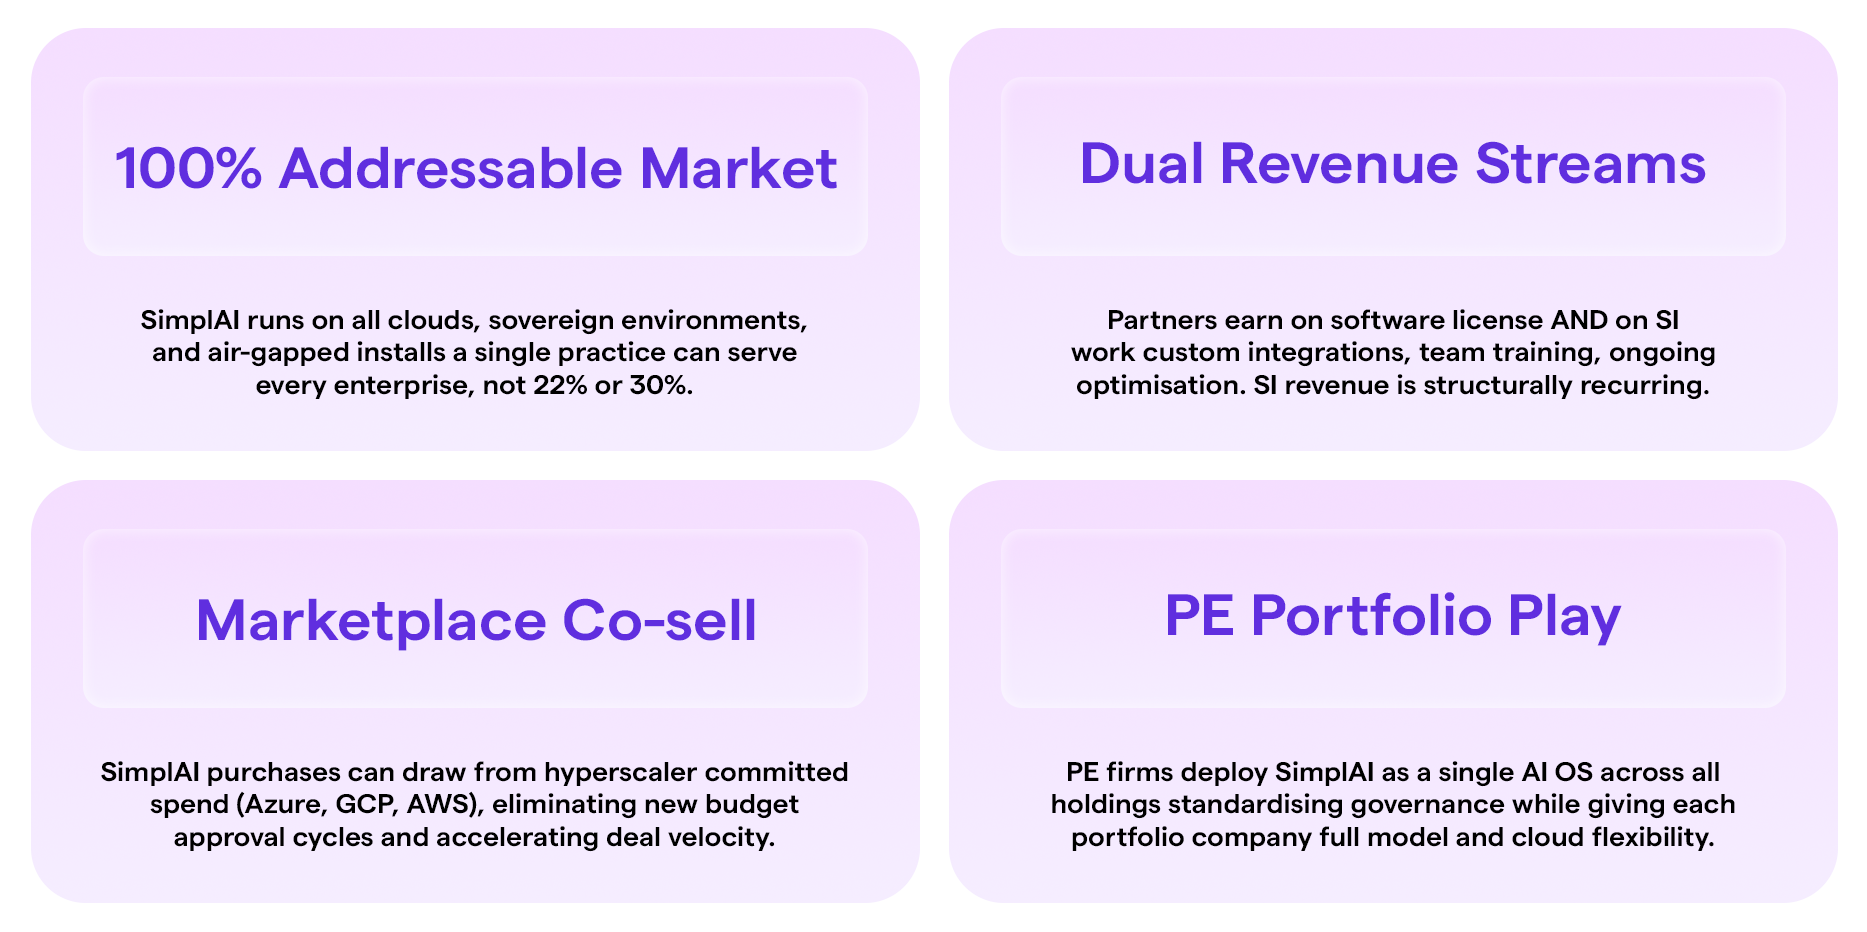
A partner building exclusively on AWS Bedrock or Azure AI Foundry is constrained to their hyperscaler’s installed base and subject to that hyperscaler’s partner tier caps. SimplAI operates across all clouds, sovereign environments, and air-gapped installations. A single SimplAI practice can serve enterprises regardless of their cloud commitment — addressing 100% of the enterprise market, not 22% or 30%.
Dual revenue streams
SimplAI partners earn on both the software license and the SI (systems integration) component — the complex workflow design, custom integration development, team training, and ongoing optimization work that every enterprise deployment requires. This SI revenue is structurally recurring and grows as enterprises expand their agentic footprint.
Marketplace co-sell advantage
SimplAI is embedded in hyperscaler marketplaces and co-sell programs. When a partner closes a SimplAI deal with an enterprise that has an Azure Committed Spend, the purchase can draw from that committed spend — eliminating new budget approval cycles and dramatically accelerating deal velocity. This is a decisive sales advantage that bypasses the most common procurement friction in enterprise AI.
Startup velocity vs. incumbent inertia
Enterprises consistently report that hyperscaler-native AI platforms move slowly: slow feature releases, slow integrations, slow support responses. SimplAI moves at startup velocity — shipping integrations, supporting bespoke use cases, and adapting to enterprise requirements at a pace that large platform companies structurally cannot match. Partners who align with SimplAI can use this velocity as a competitive differentiator in client engagements.
Private equity portfolio play: PE firms with multiple portfolio companies can deploy SimplAI as the single AI operating system across all holdings — standardizing governance, compliance, and tooling while giving each portfolio company full model and cloud flexibility. One OS, infinite companies. This is a rare enterprise software wedge that converts portfolio relationships into multi-seat, multi-year contracts at the holding company level.
Ecosystem Role
SimplAI’s Irreplaceable Position in the AI Ecosystem
Zoom out from the competitive landscape and the picture becomes even clearer. The AI ecosystem today resembles the early internet: extraordinary raw capability, fierce infrastructure competition, and a near-total absence of the middleware and governance layers that would allow organizations to reliably build on top of it. SimplAI occupies the middleware position — and middleware, historically, is where the most enduring enterprise software value accumulates.
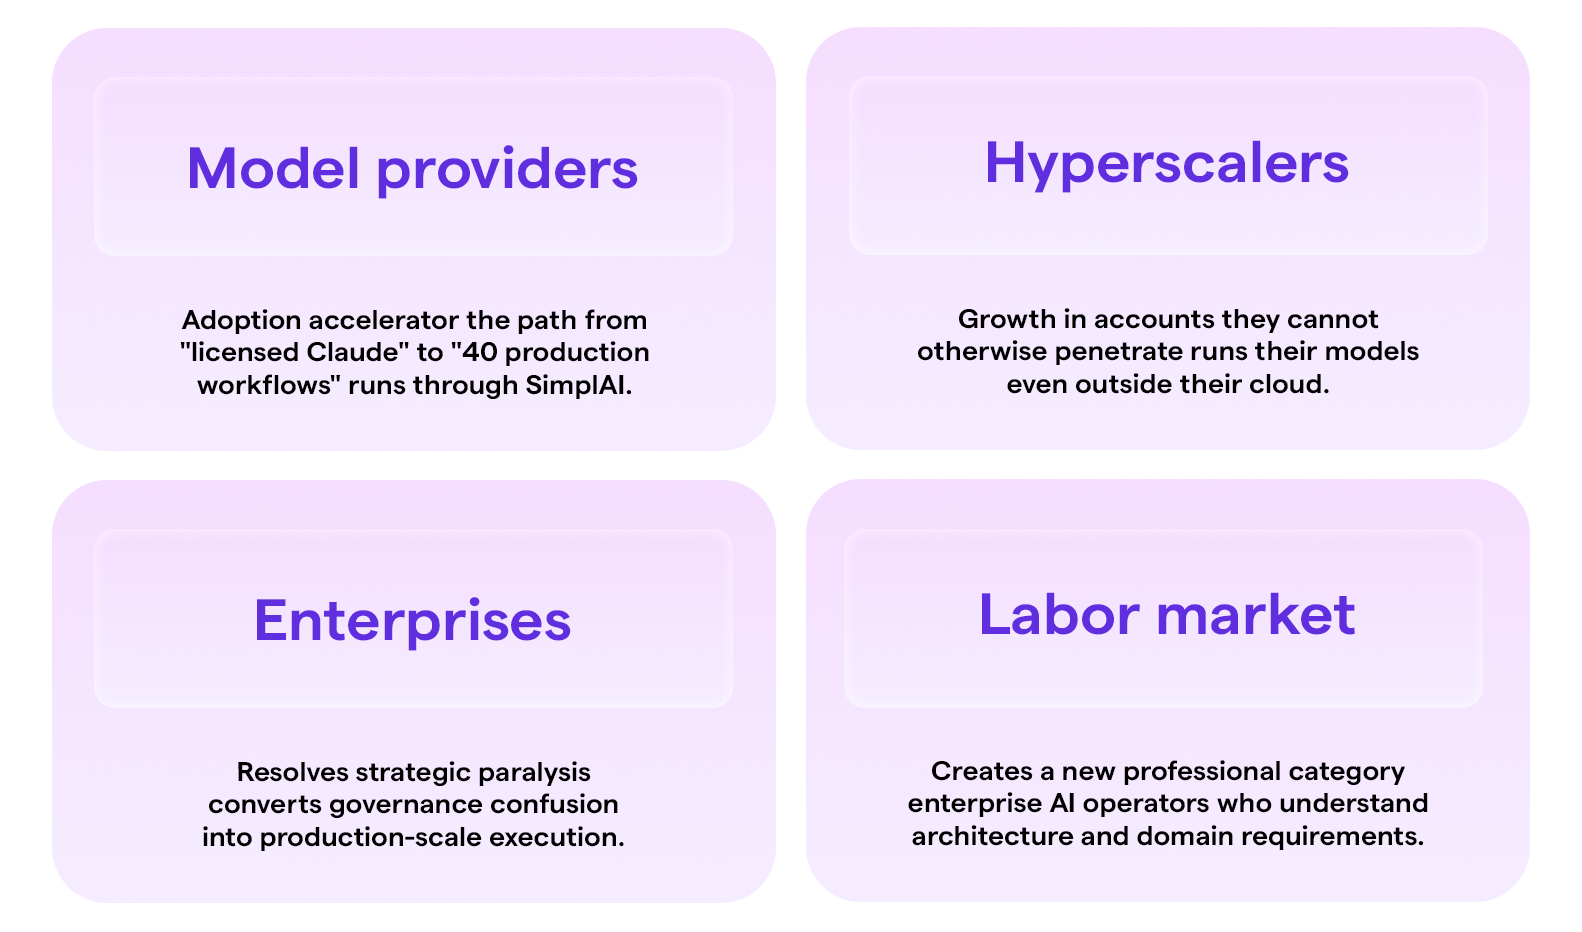
For model providers, SimplAI is an adoption accelerator. The pathway from “we licensed Claude” to “Claude is running in production across 40 enterprise workflows” runs through an orchestration and governance layer. SimplAI provides that pathway. Every enterprise that deploys SimplAI increases frontier model consumption — making model providers measurably better off.
For hyperscalers, SimplAI fills the gap that their native AI platforms leave open. GCP has 13–15% market share. The other 85% of enterprise workloads are not going to migrate their data centers to become GCP-native. SimplAI runs in those other environments — and when it does, it can still consume GCP’s Gemini models, satisfy GCP committed spend through marketplace transactions, and create a new growth vector for GCP in accounts they could not otherwise penetrate.
For enterprises, SimplAI resolves the strategic paralysis that has stalled AI adoption. CIOs and CDOs are not failing because they lack AI enthusiasm — they are failing because they lack a coherent framework for deploying AI responsibly, cost-effectively, and at scale. SimplAI provides that framework, converting strategic confusion into operational execution.
For the labor market, SimplAI’s Field Deployment Engineering model creates a new professional category: enterprise AI operators who understand both the technical architecture and the domain-specific requirements of their clients. This is not commodity labor — it is high-value expertise that grows in importance as agentic complexity increases.
“All model providers need more people like SimplAI to drive enterprise adoption. Without the governance, compliance, scale, and deployment layer, the cost just inflates and enterprises never really adopt.”
— Sandeep Dinodiya, SimplAI
Conclusion
The Operating System Imperative
The central thesis of this paper can be stated simply: enterprises do not need more AI. They need governance over the AI they already have. The next two to three years of enterprise AI investment will not be determined by which models are most capable — every frontier model will be sufficiently capable. It will be determined by which organizations can govern, orchestrate, secure, and scale AI deployments across thousands of concurrent agents, multiple clouds, multiple models, and increasingly complex compliance requirements.
SimplAI is the only platform purpose-built to solve this problem at enterprise scale. It is cloud-agnostic. It is model-agnostic. It deploys in air-gapped environments. It provides budget governance down to the application level. It enables cross-organizational reuse through an internal agent and skill marketplace. It embeds in hyperscaler marketplaces and satisfies committed cloud spend. And it comes with Field Deployment Engineers who ensure that the investment converts to measurable business outcomes.
The question is no longer whether enterprises need an AI operating system. The question is which one. As this paper has argued across eight sections, neither hyperscalers, nor model providers, nor open-source frameworks can deliver the full six-pillar architecture that enterprise AI adoption demands. SimplAI can. SimplAI does.
For enterprises ready to move beyond pilots and governance paralysis. For partners ready to build a practice with unlimited market ceiling and dual revenue streams. For the AI ecosystem ready to see enterprise adoption finally scale — SimplAI is the operating system the moment has been waiting for.
The enterprise that runs on a thousand agents needs an OS, not a tool.
SimplAI is that operating system — the infrastructure layer that turns scattered AI investment into governed, compliant, scalable, production-grade enterprise intelligence.
Author bio