Banks still take 18 to 25 days to process a mortgage application. In an era when a consumer can open a brokerage account in eight minutes, that number should read as an institutional crisis — not a benchmark.
The financial services industry is sitting on a paradox. It has digitized aggressively — mobile banking, API-first cores, cloud migration, yet the underlying decision workflows remain stubbornly human, linear, and slow. Credit analysts still manually aggregate data across five platforms. KYC teams spend hours chasing document resubmissions. Loan officers work from paper-based checklists. Debt recovery runs on call center intuition.
The gap between what technology can deliver and what BFSI operations actually experience has never been wider. And the institutions that recognize this inflection point and act on it, will dominate the next decade of financial services.
That inflection point has a name: Agentic AI.
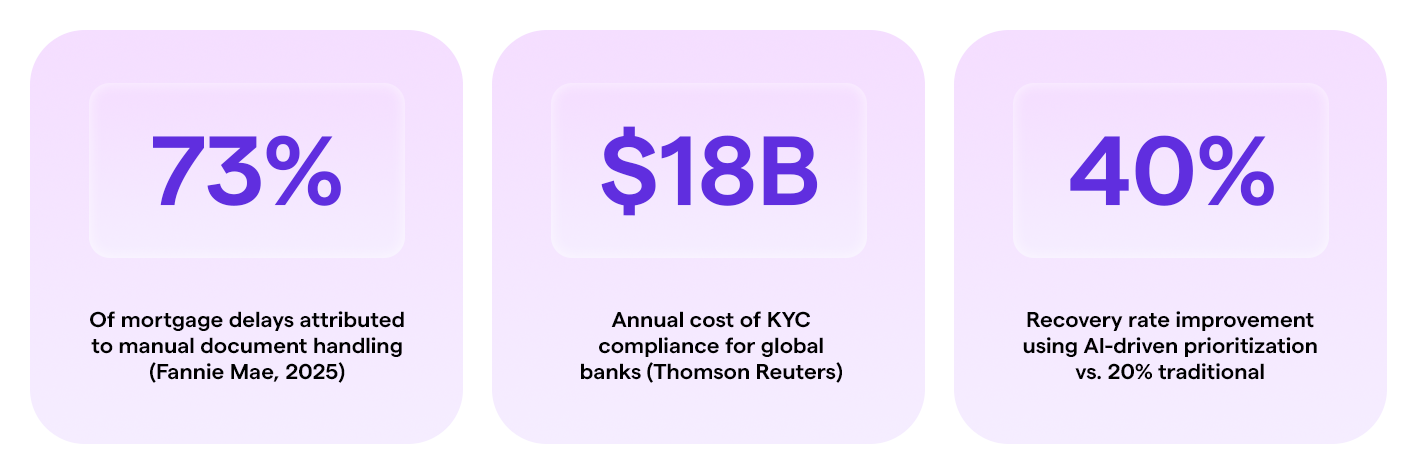
What Is Agentic AI in Banking — and Why Does It Matter Now?
Traditional AI in banking was fundamentally reactive. You fed it data, it returned a prediction or classification. A fraud score. A credit probability. A document classification label. It was useful, but passive. It waited to be called.
Agentic AI is fundamentally different. An AI agent doesn’t wait. It reasons, plans, takes actions, monitors outcomes, and adjusts course, autonomously. Given a goal like “process this mortgage application end-to-end,” an agentic system will retrieve documents, cross-reference against income databases, run compliance checks, flag anomalies, escalate edge cases to a human reviewer, and generate the final underwriting summary, without a human orchestrating each step.
The distinction matters enormously in BFSI:
- Traditional AI: Predicts credit risk → human takes action
- Agentic AI: Predicts credit risk → pulls supporting data → structures the decision memo → routes for approval → updates the CRM
Key Definition: Agentic AI refers to AI systems that can set goals, decompose them into sub-tasks, take sequential actions using tools and data sources, and self-correct , with minimal human intervention. In BFSI, this translates to end-to-end automation of workflows that previously required human judgment at every step.
This shift from AI-as-tool to AI-as-operator is what makes 2026 a threshold moment. The infrastructure large language models, multimodal document understanding, orchestration frameworks, and enterprise-grade deployment platforms has matured enough to make genuinely autonomous BFSI workflows commercially viable.
Key Use Cases: Where Agentic AI Is Transforming BFSI Operations
AI in Mortgage Loan Processing: From 18 Days to Under 5
A conventional mortgage application passes through seven to nine handoffs before a decision is reached. Document collection, initial review, property appraisal scheduling, title search, underwriting, compliance check, final approval each step is discrete, often siloed, and frequently delayed by human availability and manual data entry.
The result: industry-average processing times of 18 to 25 days, with some complex cases dragging past 45. Customer satisfaction erodes. Loan officers burn time on administrative tasks rather than complex judgment calls. And operational costs stay stubbornly high.
Ai Mortgage processing automation
HOW AGENTIC AI SOLVES MORTGAGE PROCESSING
- Intelligent Document Processing (IDP): Automatically extracts, classifies, and validates data from W-2s, bank statements, tax returns, and pay stubs — handling handwritten, scanned, and digital formats with high accuracy
- Real-Time Underwriting Support: Aggregates borrower financial data, property comps, and risk parameters to generate a structured underwriting memo within minutes
- Compliance Automation: Runs TRID, HMDA, and RESPA checks in parallel, flagging deviations before they become regulatory issues
- Dynamic Escalation: Routes only genuinely complex edge cases — co-borrower discrepancies, unusual income structures — to human underwriters
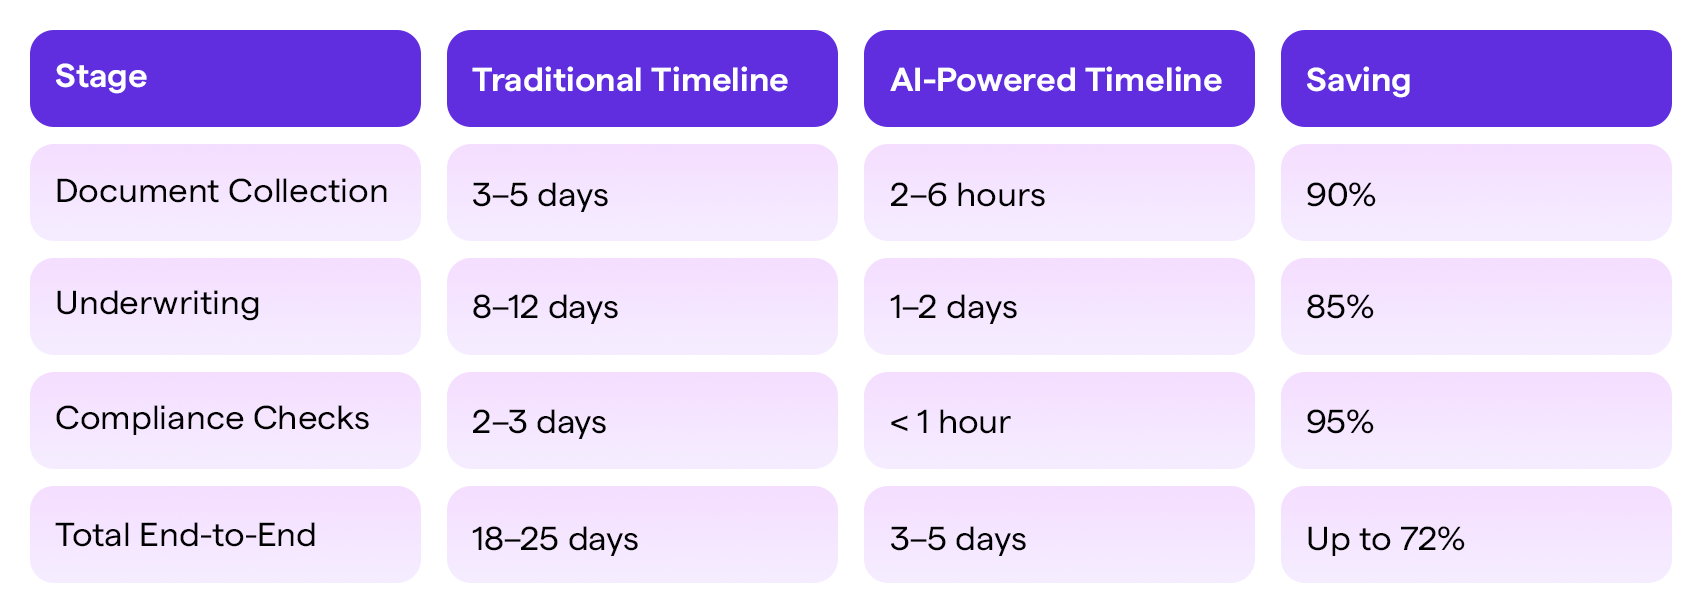
SimplAI mortgage processing agents integrate natively with existing LOS platforms — no rip-and-replace. The system handles multi-format document ingestion, compliance rule orchestration, and structured output generation, reducing processing time by up to 72% while maintaining full audit trails for regulatory review.
AI Credit Analyst Agent: Redefining Risk Intelligence
A senior credit analyst can meaningfully assess perhaps 8 to 12 complex commercial files per day. They work from fragmented data — pulling bureau reports, financial statements, industry benchmarks, and news feeds across multiple platforms — and synthesize it through a process that is inherently sequential and cognitively exhausting.
This model has two critical failure modes. First, throughput: as loan volumes scale, analyst capacity becomes the bottleneck. Second, consistency: credit judgments made at 9 AM differ from those made at 4 PM. Fatigue, recency bias, and anchoring affect even the best analysts.
WHAT AN AI CREDIT ANALYST AGENT ACTUALLY DOES
- Multi-source data aggregation: Pulls bureau data, financial statements, GST returns, bank transaction patterns, and sector reports in seconds
- Dynamic risk scoring: Applies configurable models — not static scorecards — that adapt to borrower type, loan purpose, and macroeconomic context
- Qualitative signal extraction: Analyzes management commentary, news sentiment, and sector headwinds using language understanding
- Explainable outputs: Generates structured credit memos with reasoning chains, not black-box scores — critical for regulatory defensibility
- Predictive flags: Surfaces early warning indicators — covenant breach probability, cash flow stress signals — before they materialize
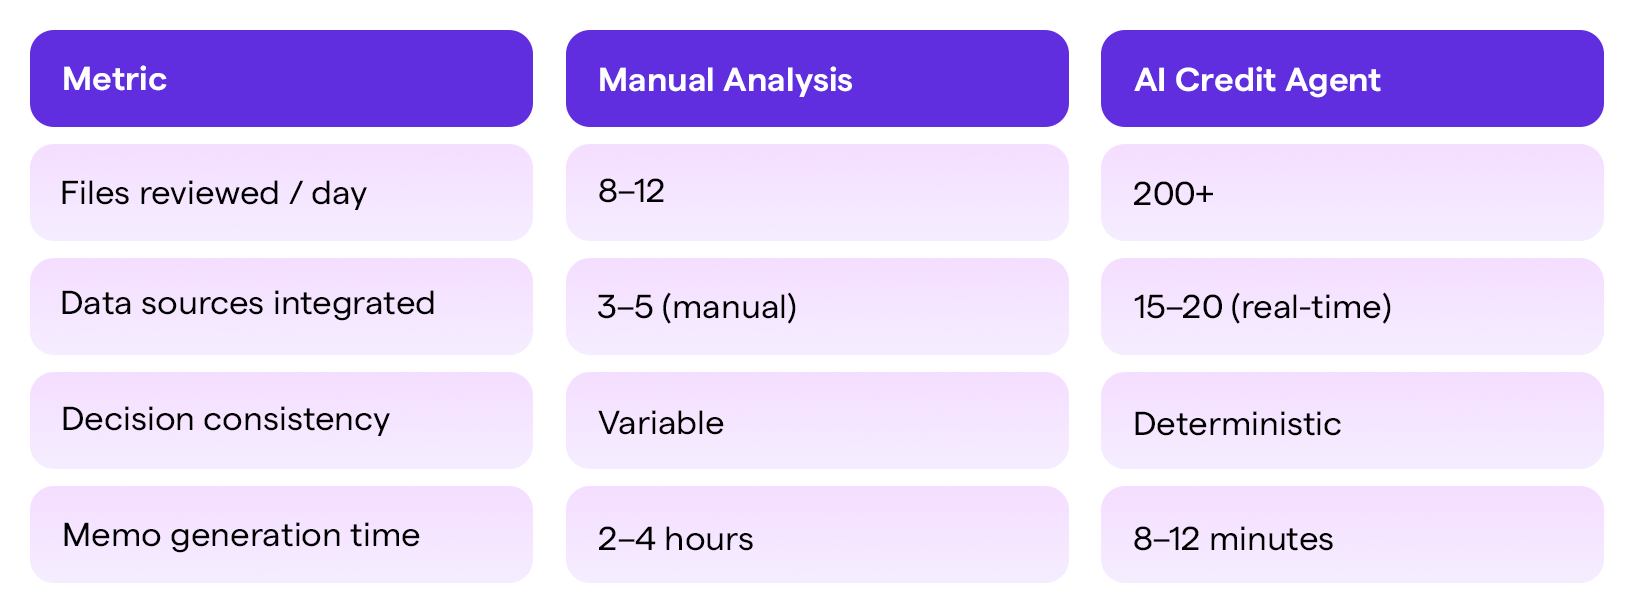
SimplAI Credit Analyst Agent is designed for both retail and commercial credit workflows. It generates IFRS 9-aligned risk assessments, integrates with core banking systems via API, and maintains a complete audit trail — ensuring AI-assisted decisions remain defensible under regulatory scrutiny.
KYC Automation AI: Compliance Without the Friction
Global banks collectively spend over $18 billion annually on KYC compliance (Thomson Reuters, 2025). For mid-sized institutions, KYC can consume 20% of operations headcount. Manual onboarding for corporate customers can take 30 to 90 days. Customer drop-off rates during onboarding routinely exceed 40% in digital channels when the process feels laborious.
Worse, manual KYC is not just slow — it is inconsistently applied. The same document set processed by different analysts can yield different risk ratings. In an era of increasingly sophisticated financial crime, inconsistency is a liability.
AGENTIC KYC: WHAT THE AUTOMATION ACTUALLY COVERS
- Document verification: Automated extraction and validation of identity documents, utility bills, corporate registrations, and beneficial ownership structures across 190+ countries
- AML screening: Real-time cross-referencing against global sanctions lists, PEP databases, and adverse media — with continuous monitoring, not just point-in-time checks
- Entity resolution: AI-driven disambiguation of corporate structures, shell company detection, and UBO identification
- Risk tiering: Automatic assignment of Low / Medium / High risk ratings with documented rationale — reducing manual review queue by 60–80%
- Ongoing monitoring: Perpetual KYC (pKYC) triggers when a customer’s risk profile changes — eliminating the rigid three-year refresh cycle
How AI Agents Automate KYC Verification Process End-to-End
Regulatory Trend: Regulators in the EU, UK, and Singapore are moving toward outcomes-based KYC frameworks that reward automated, auditable processes. Institutions deploying structured AI systems are better positioned to demonstrate systemic compliance — not just case-by-case adherence.
SimplAI KYC automation layer handles both onboarding and ongoing monitoring within a single orchestration framework. It is jurisdiction-configurable, supports multi-language documents, and generates regulator-ready audit packs for every decision — reducing KYC operations cost by up to 65% in documented deployments.
AI in Debt Collection: Intelligent Recovery, Human Dignity
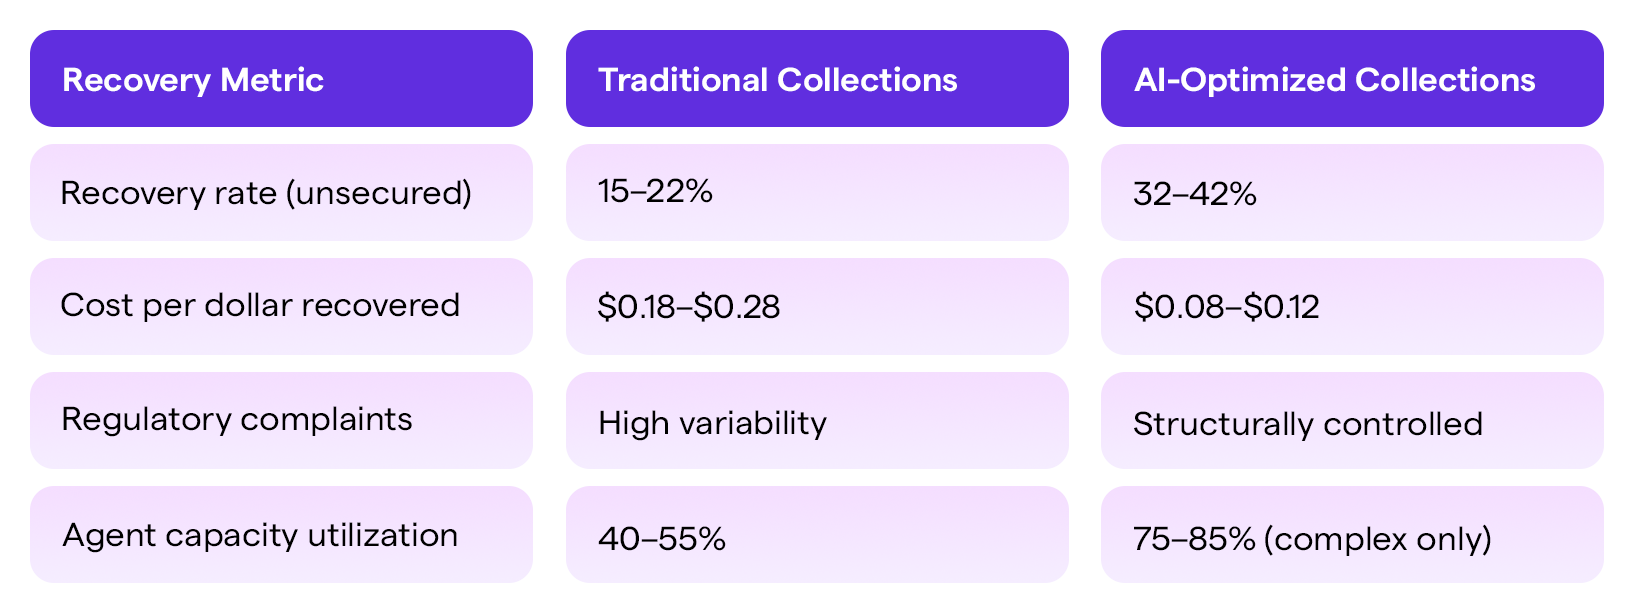
Conventional debt recovery is a blunt instrument. Accounts are typically segmented by DPD bucket, assigned to call center agents working from scripts, and contacted via phone at predetermined intervals. Recovery rates for unsecured consumer debt average 15–22% using this approach — a figure that has barely moved in a decade.
The problem isn’t effort; it’s intelligence. Not every 60-DPD borrower has the same propensity to pay. Not every account responds to the same communication channel. Managing this complexity at scale is beyond human capacity.
AI-DRIVEN COLLECTIONS: WHAT CHANGES
- Propensity-to-pay scoring: ML models trained on transaction behavior, employment signals, and engagement history predict which accounts are most likely to respond — and when
- Channel optimization: AI selects email, SMS, IVR, or human call based on borrower preference patterns and response history
- Dynamic offer generation: Personalized settlement offers, restructuring options, and hardship plans generated in real time based on borrower financial capacity signals
- Tone and sentiment calibration: Communication language adapts to borrower profile — avoiding aggressive language that triggers regulatory complaints
- Regulatory guardrails: Built-in FDCPA, FCA, and RBI compliance rules prevent violations at the point of communication generation
Loan Document Checklist Automation: Eliminating Last-Mile Errors
Every loan type carries a document checklist, home loans require 15 to 25 documents, MSME loans can demand 30 to 40. These checklists are managed manually in most institutions: loan officers compare submissions against static lists, often in spreadsheets or basic document management systems.
The error rate is consistently underestimated. Missing income proofs, expired identity documents, incorrect property survey reports — these are daily operational friction that delays approvals, frustrates applicants, and drives up per-loan processing costs.
WHAT AI-DRIVEN DOCUMENT VALIDATION DELIVERS
- Dynamic checklist generation: AI tailors the required document set based on loan type, borrower profile, property type, and jurisdiction — not a static template
- Completeness scoring: Real-time assessment of submission completeness with a percentage score and specific missing-item identification
- Validity checking: Automated expiry date detection, signature verification, and cross-document consistency checks (e.g., name matching across PAN, Aadhaar, and bank statement)
- Applicant-facing gap communication: Automated, specific requests for missing items — not generic “your application is incomplete” messages that confuse applicants
Institutions deploying intelligent document validation report a 45–60% reduction in re-work cycles and a measurable improvement in application-to-approval conversion rates.
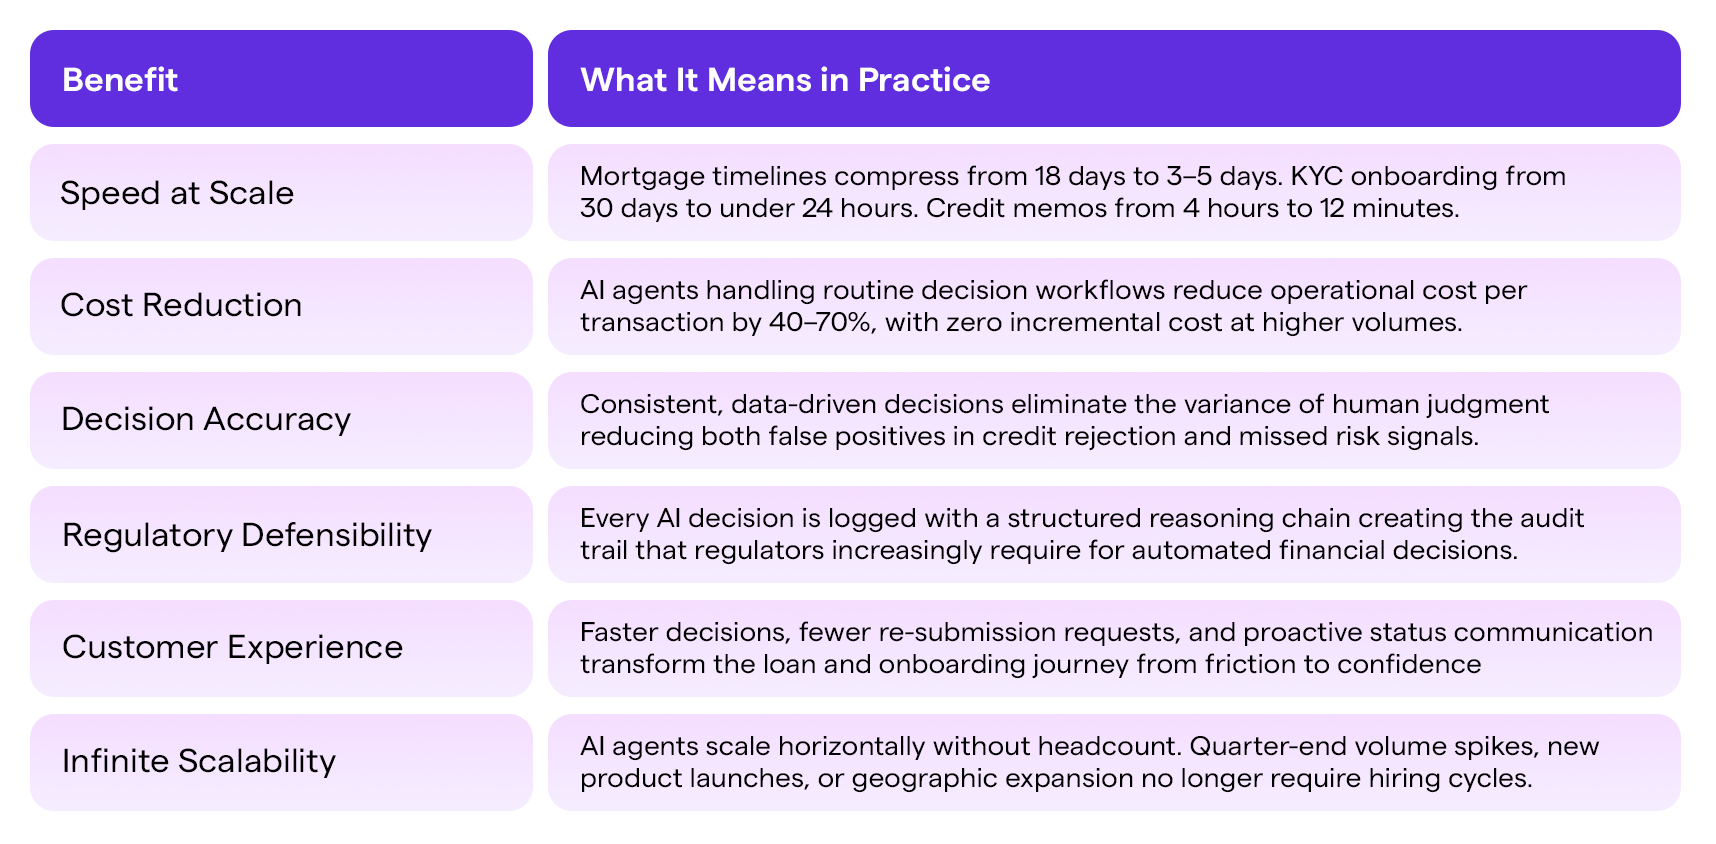
The Strategic Benefits of Agentic AI Across BFSI
Industry Trends Shaping BFSI AI in 2026
THE WORKFORCE IS EVOLVING, NOT DISAPPEARING
The narrative of AI replacing banking jobs misses the more accurate story: the nature of banking work is changing. The evolution follows a clear arc — from AI copilots (tools that assist humans) to AI agents (systems that act on behalf of humans) to what some are now calling an AI workforce — collections of specialized agents working in orchestrated parallel.
In this model, human bankers concentrate on genuinely complex judgment calls: restructuring a distressed corporate borrower, navigating a sensitive large-ticket credit decision, managing an institutional relationship. The AI agent workforce handles everything that is definable, repeatable, and rule-governed — which, honestly, constitutes the majority of banking operations volume.
REGULATORY FRAMEWORKS ARE CATCHING UP
The EU AI Act, the Bank of England’s model risk guidance, and the RBI’s evolving stance on algorithmic credit decisioning share a common thread: they don’t prohibit AI in financial decisions — they require it to be explainable, auditable, and non-discriminatory. This is not a headwind for agentic AI; it’s a design requirement that mature platforms already meet.
COMPETITIVE PRESSURE IS ACCELERATING
Digital-native lenders — fintechs, neobanks, embedded finance platforms — are already operating with AI-first underwriting. They approve loans in minutes. They onboard in hours. Traditional banks that continue to compete on brand legacy alone will find that advantage eroding faster than their transformation timelines.
Why SimplAI: A Transformation Partner, Not a Point Solution
The BFSI AI landscape is crowded with point solutions, a KYC tool here, a credit scoring API there, a document extraction module elsewhere. The problem with this approach is integration debt. Each siloed tool requires its own data pipeline, its own monitoring, its own vendor relationship.
SimplAI architecture is fundamentally different. It operates as a modular agentic platform — purpose-built AI agents for specific BFSI workflows that share a common orchestration layer, memory system, and compliance framework.
- An insight surfaced in credit analysis is available to the document validation agent and the KYC agent — contextually, in real time
- A risk flag raised during KYC can automatically trigger enhanced due diligence in the credit workflow without human re-routing
- A change in regulatory requirements can be applied once, centrally, and propagated across all agents — not patched individually across ten separate tools
Enterprise deployment is built into the platform DNA — SOC 2 Type II compliance, on-premises and private cloud options, configurable guardrails for each institution’s risk appetite, and integrations with leading core banking, LOS, and CRM systems.
The Future of AI in Banking: What 2027 and Beyond Looks Like
FULLY AUTONOMOUS END-TO-END WORKFLOWS
The next generation won’t just automate steps within a workflow — it will manage entire product lifecycles. From initial lead qualification through application, underwriting, disbursement, servicing, and eventual closure or renewal, AI will orchestrate the full customer journey with human oversight reserved for defined exception thresholds.
HYPER-PERSONALIZED FINANCIAL SERVICES AT POPULATION SCALE
Today’s personalization is segmentation. Tomorrow’s is truly individual. AI systems with persistent memory of a customer’s full financial history will make product recommendations, proactively flag risks, and adjust credit terms in real time based on actual financial behavior rather than static scoring.
ANTICIPATORY RISK MANAGEMENT
The most significant shift will be in risk: from detection to prediction. Rather than identifying a customer who has defaulted, AI systems will surface the combination of signals, income compression, irregular transaction patterns, sector-level stress that predict default 90 to 180 days ahead of occurrence.
Conclusion: The Window for Competitive Advantage Is Open — Not Indefinitely
Here is the honest assessment: agentic AI in BFSI is not a future technology being debated in research labs. It is a present reality, already deployed in production at institutions that are actively compressing their operational timelines, cutting their per-transaction costs, and improving their customer satisfaction scores, simultaneously.
The question for banking leaders is not whether to adopt agentic AI. That question was settled by the economics two years ago. The question is whether your institution will be among the cohort that captures first-mover advantage in your market, or whether you will be playing catch-up to competitors who moved decisively while you ran pilots.
The strategic imperative is clear: BFSI leaders who treat agentic AI as a long-term roadmap item, rather than an urgent operational priority are making a competitive choice. They are choosing to cede ground that will be increasingly difficult to recover.
Frequently Asked Questions
What is agentic AI in banking?
Agentic AI in banking refers to AI systems that autonomously execute complex, multi-step financial workflows — such as loan processing, KYC, and credit analysis — without requiring human orchestration at each step. Unlike traditional AI tools that predict or classify, agentic systems reason, plan, take actions using integrated tools and data sources, and self-correct based on outcomes. The result is end-to-end automation of workflows that previously required constant human judgment and intervention.
How does AI reduce mortgage processing time?
AI reduces mortgage processing time by automating the most time-consuming steps: document collection and validation, underwriting data aggregation, compliance checks, and decision memo generation. Tasks that previously required days of human coordination are completed in minutes. Industry benchmarks show AI-enabled mortgage pipelines compressing average processing from 18–25 days to 3–5 days, with the most optimized deployments reaching same-day conditional approval for standard applications.
Is AI safe for KYC and compliance?
Yes — when properly architected, AI-driven KYC is more reliable than manual processes, not less. Enterprise-grade KYC automation systems generate a full audit trail for every decision, apply consistent rule sets that eliminate individual analyst variance, and run continuous monitoring rather than periodic reviews. Regulators in the EU, UK, and Singapore are actively moving toward outcomes-based compliance frameworks that reward systematic, auditable AI processes.
How does AI improve debt collection?
AI improves debt collection by replacing blunt DPD-bucket segmentation with individual-level propensity-to-pay modeling, channel optimization, and dynamic offer generation. Rather than contacting every delinquent account with the same script, AI systems identify which accounts are most likely to respond, through which channel, with which offer. This approach consistently produces recovery rate improvements of 15–20 percentage points over traditional methods.
What is the ROI timeline for implementing agentic AI in banking?
Well-structured implementations typically reach measurable payback within 6–12 months. Operational cost reductions (40–70% per transaction in automated workflows), speed improvements that directly reduce cost-per-loan, and revenue impact from higher application-to-approval conversion rates combine to produce strong business cases. Modular, workflow-specific deployments that go live in 90-day increments consistently outperform large, monolithic transformation programs.
Ready to Move from Pilot to Production?
Explore how SimplAI agentic platform can transform your BFSI operations — with a structured business case and 90-day deployment milestones.
Request a Strategic Briefing
Author bio