What Is Intelligent Document Processing for Mortgages?
Intelligent Document Processing (IDP) for mortgages is an AI-powered technology that automatically ingests, classifies, reads, and extracts data from loan documents — including W-2s, tax returns, bank statements, title docs, and regulatory disclosures. Unlike basic OCR, IDP uses machine learning to understand document context, validate extracted data, and integrate directly with Loan Origination Systems (LOS). It replaces the manual document handling that typically consumes 40–60% of a loan processor’s time.
The Document Problem at the Heart of Every Mortgage
Ask any loan officer what slows them down and the answer is almost always the same: documents. The average residential mortgage file requires between 400 and 600 pages of supporting documentation. These pages arrive in every format imaginable — PDFs, photos taken on smartphones, faxes, scanned photocopies, and handwritten notes. They arrive out of order, incompletely, and sometimes multiple times as borrowers send corrected versions.
A loan processor at a typical regional bank or mortgage company will spend 60 to 80 hours per month doing nothing but managing documents — requesting them, receiving them, sorting them, checking for completeness, extracting data from them, and entering that data into the LOS. This is not value-added work. It is mechanical labor that AI is now purpose-built to perform, faster and more accurately than any human can.
Intelligent Document Processing is the specific category of AI technology designed to solve this problem. This guide is the complete reference for loan officers, operations managers, and lending technology teams who want to understand what IDP is, how it differs from simpler OCR technology, and how it works across every stage of the mortgage document workflow.
What Is Intelligent Document Processing?
Intelligent Document Processing is a category of artificial intelligence technology that combines multiple AI capabilities — optical character recognition, natural language processing, computer vision, and machine learning — to automate the end-to-end handling of documents.
The key word is intelligent. Traditional document automation tools could only do two things: convert a scanned image to searchable text (OCR) or extract data from predefined fields in structured templates. IDP does far more:
- It classifies documents automatically — determining whether a file is a W-2, a bank statement, a purchase agreement, or a driver’s license — without any human labeling.
- It extracts data from both structured and unstructured documents, including handwritten content and documents with variable formatting.
- It understands context — recognizing that the number on line 37 of a Form 1040 represents adjusted gross income, not just a numerical value.
- It validates data by cross-referencing extracted values against other documents in the file, flagging inconsistencies that may indicate errors or fraud.
- It improves over time — using machine learning to continuously refine extraction accuracy based on human corrections.
IDP vs. OCR: Why the Distinction Matters for Mortgage Lenders
Many lenders have already invested in OCR (Optical Character Recognition) technology and believe they have a “document automation” solution in place. Understanding the difference between OCR and IDP is critical to understanding the gap between where you are and what is now possible.
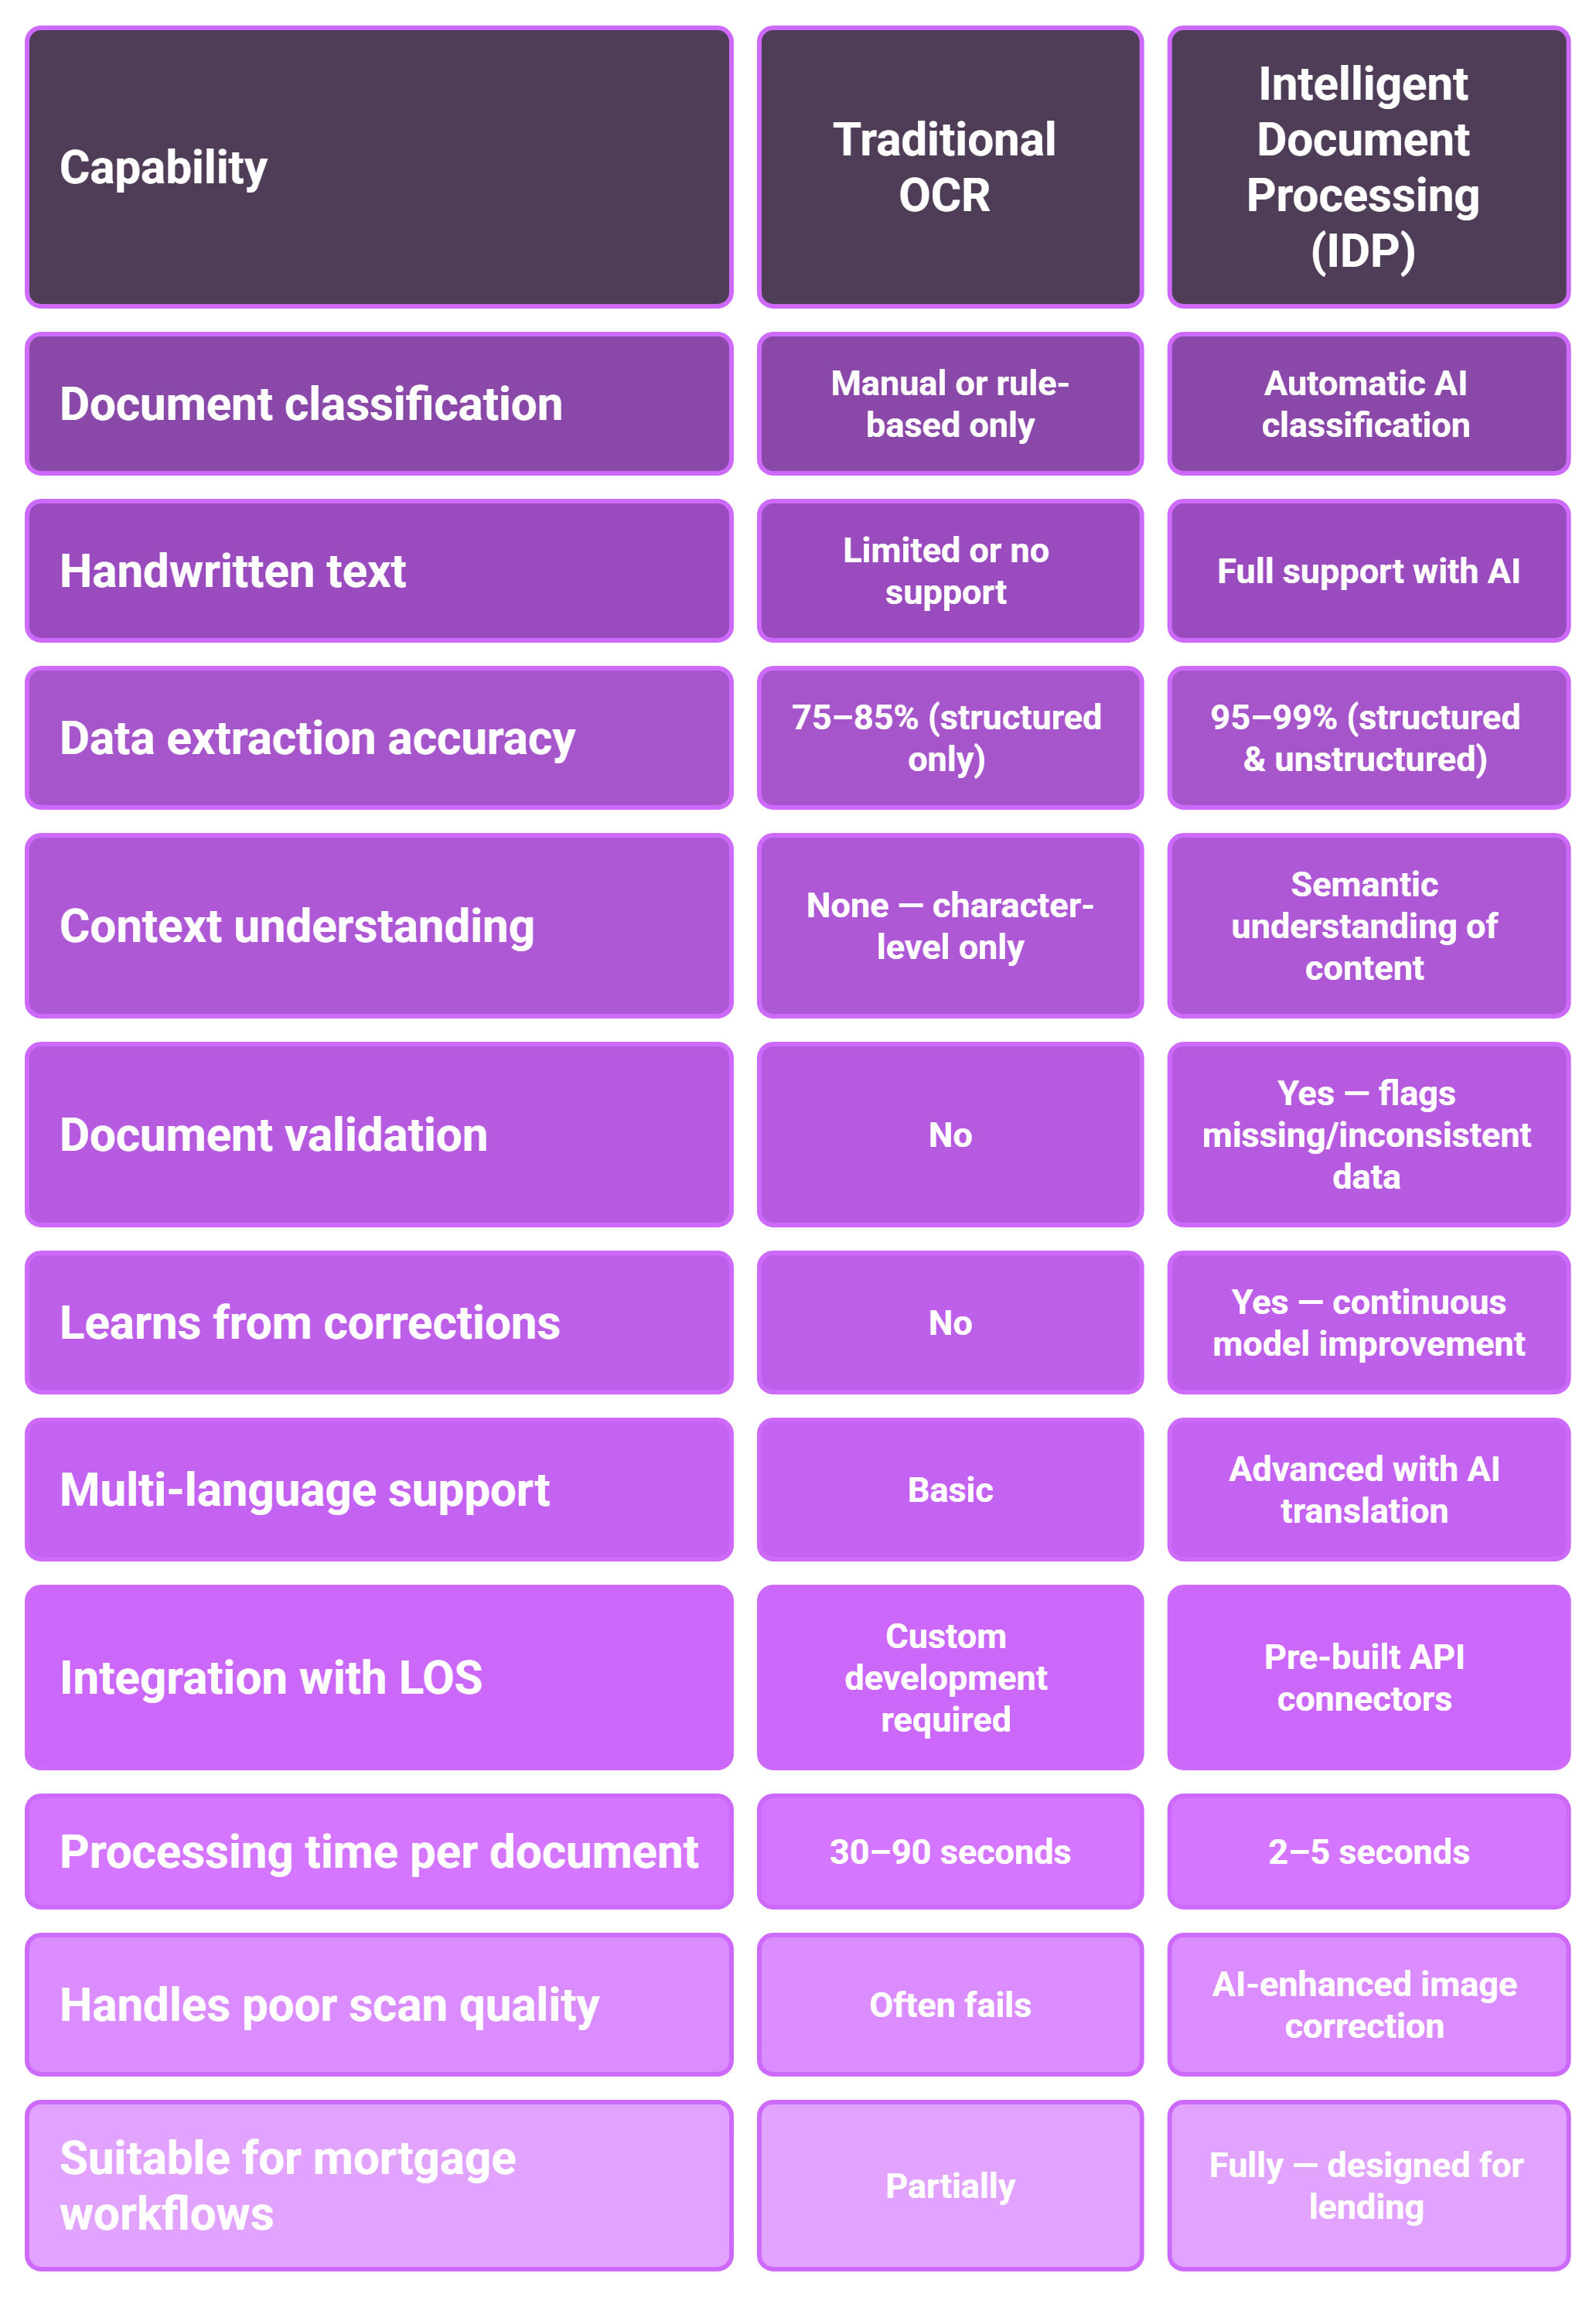
OCR is a technology that converts images of text into machine-readable text. It was designed to digitize printed documents, and it does that reasonably well for clean, structured documents with consistent formatting. What it cannot do: understand what the text means, handle variable document formats, process handwriting reliably, or validate the accuracy of extracted data.
IDP builds on OCR and goes dramatically further. It uses AI to understand document structure, extract meaning from unstructured content, validate data against business rules, integrate with downstream systems, and improve accuracy through continuous learning. For mortgage document workflows — which involve hundreds of document types in variable formats — this difference is the difference between a digital filing cabinet and a fully automated processing system.
The comparison table below details the capability differences across the dimensions that matter most for mortgage lenders:
How IDP Works in a Mortgage Document Workflow
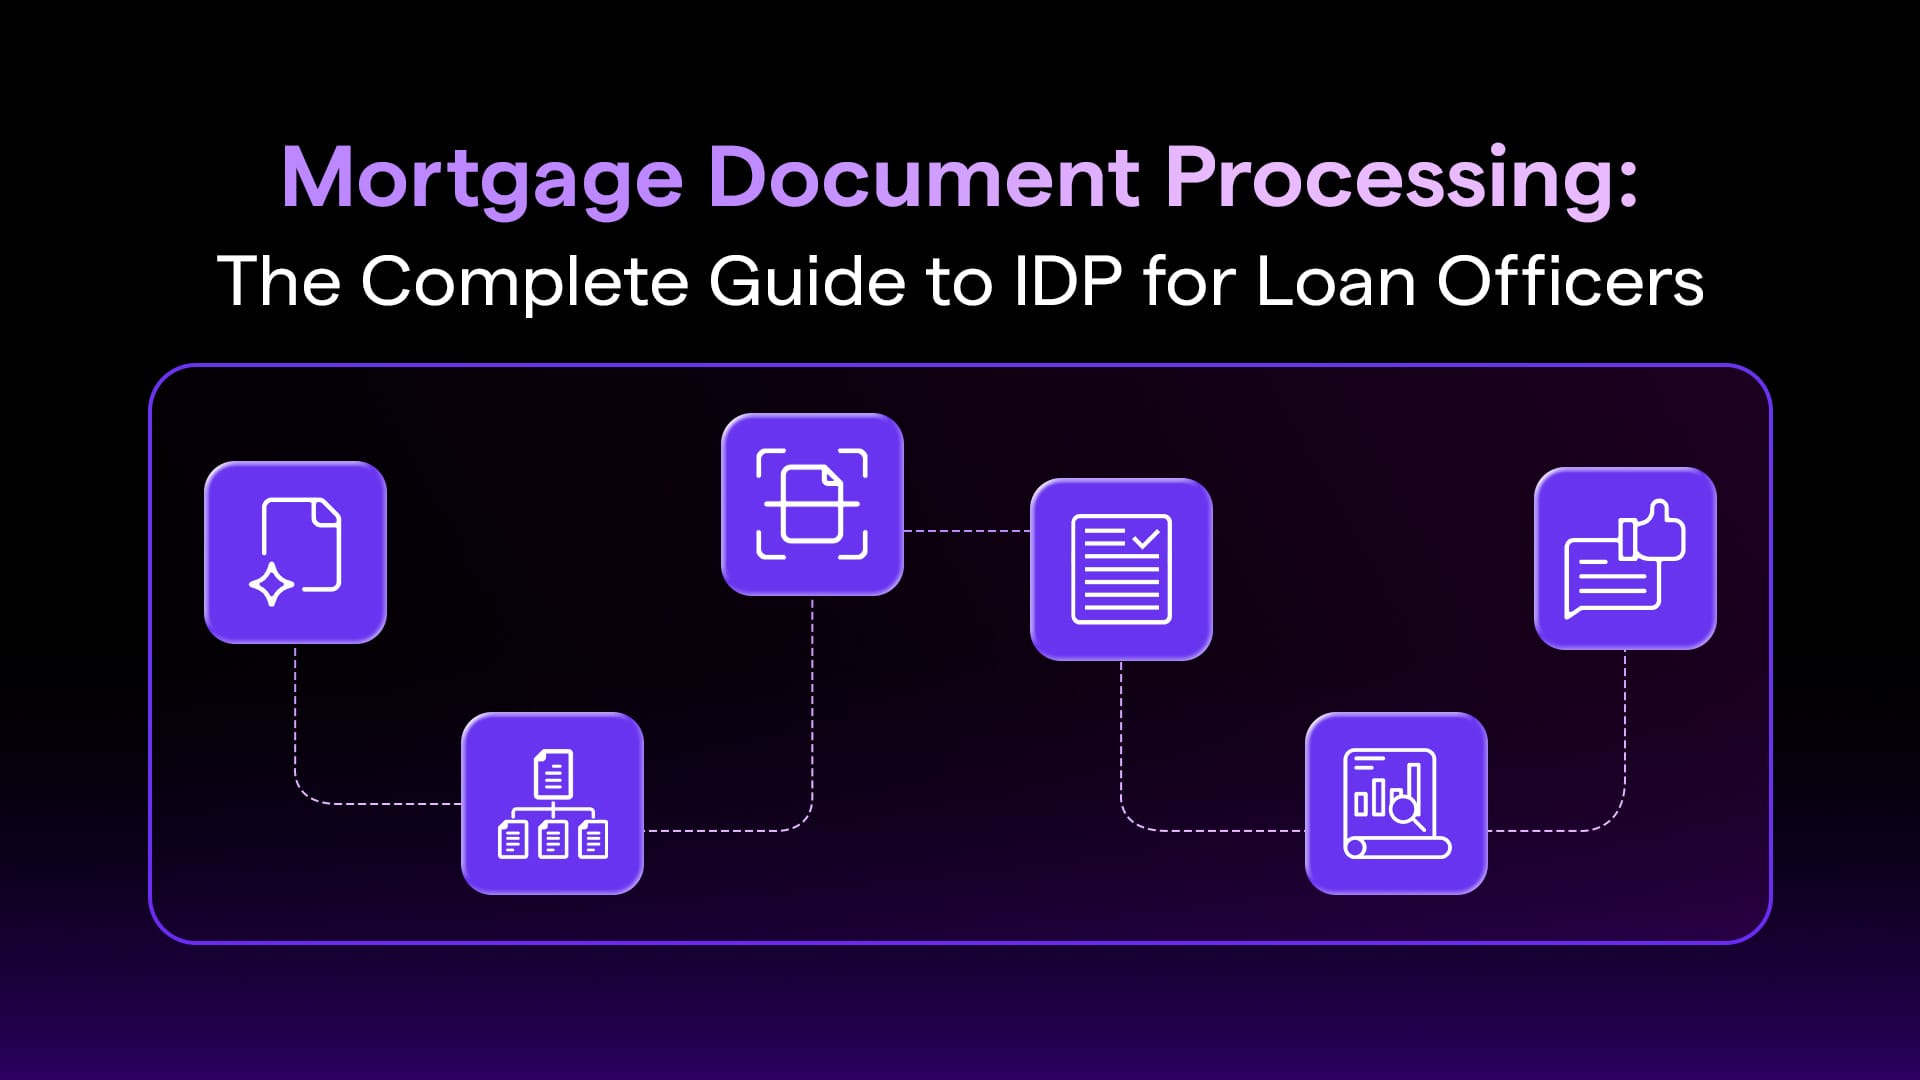
To understand IDP’s impact concretely, it helps to walk through exactly what happens when a borrower submits their loan documentation through an AI-powered lending platform:
Step 1: Document Ingestion
The borrower uploads documents through a digital portal — or, in hybrid workflows, the processor scans and uploads physical documents. The IDP system accepts files in any format: PDF, JPEG, PNG, TIFF, Word documents, Excel files. File size and quality are normalized automatically.
Step 2: Automatic Classification
Within seconds of receipt, the IDP AI analyzes each file and classifies it into a document type category. It does not require consistent file naming or manual sorting. A file named “scan_001.pdf” that contains a Form W-2 will be correctly identified as a W-2, cross-referenced against the borrower’s stated income, and placed into the appropriate file section automatically.
Modern IDP systems trained on mortgage documents can classify over 200 distinct document types, including edge cases like amended tax returns, non-traditional income letters, and foreign national documentation.
Step 3: Data Extraction
Once classified, the IDP system extracts all relevant data fields from each document. For a Form W-2, this includes employer name and EIN, employee name and SSN, wages in boxes 1–20, federal and state withholdings, and the tax year. For a bank statement, it extracts account holder name, account number, bank name, all transaction entries, beginning and ending balances, and average daily balance — and recalculates totals to verify they are internally consistent.
Extraction accuracy for structured documents like tax forms typically exceeds 99%. For less structured documents — like letters from CPAs or non-standard employment agreements — modern IDP systems achieve 95–97% accuracy on first pass, with the AI flagging low-confidence extractions for human review rather than silently producing errors.
Step 4: Validation and Cross-Document Reconciliation
This is where IDP separates itself most decisively from OCR. After extraction, the IDP system validates data both internally (checking that figures on a document are internally consistent) and across documents (cross-referencing income reported on a W-2 against income stated on the loan application, or confirming that an employer name on a pay stub matches the employer on a VOE form).
Inconsistencies are flagged immediately with a specific explanation — “Borrower’s name on bank statement does not match loan application” or “W-2 wages do not match stated monthly income on 1003 within acceptable variance” — giving the loan processor a precise action item rather than a vague alert.
Step 5: LOS Integration and Data Population
Once extraction and validation are complete, the IDP system writes extracted data directly into the LOS. Fields that have been verified by cross-document validation are populated with high confidence. Fields that have exceptions are flagged for review. This eliminates the re-keying step entirely for the majority of file data, reducing both time and error rates dramatically.
What IDP Does With Each Type of Mortgage Document
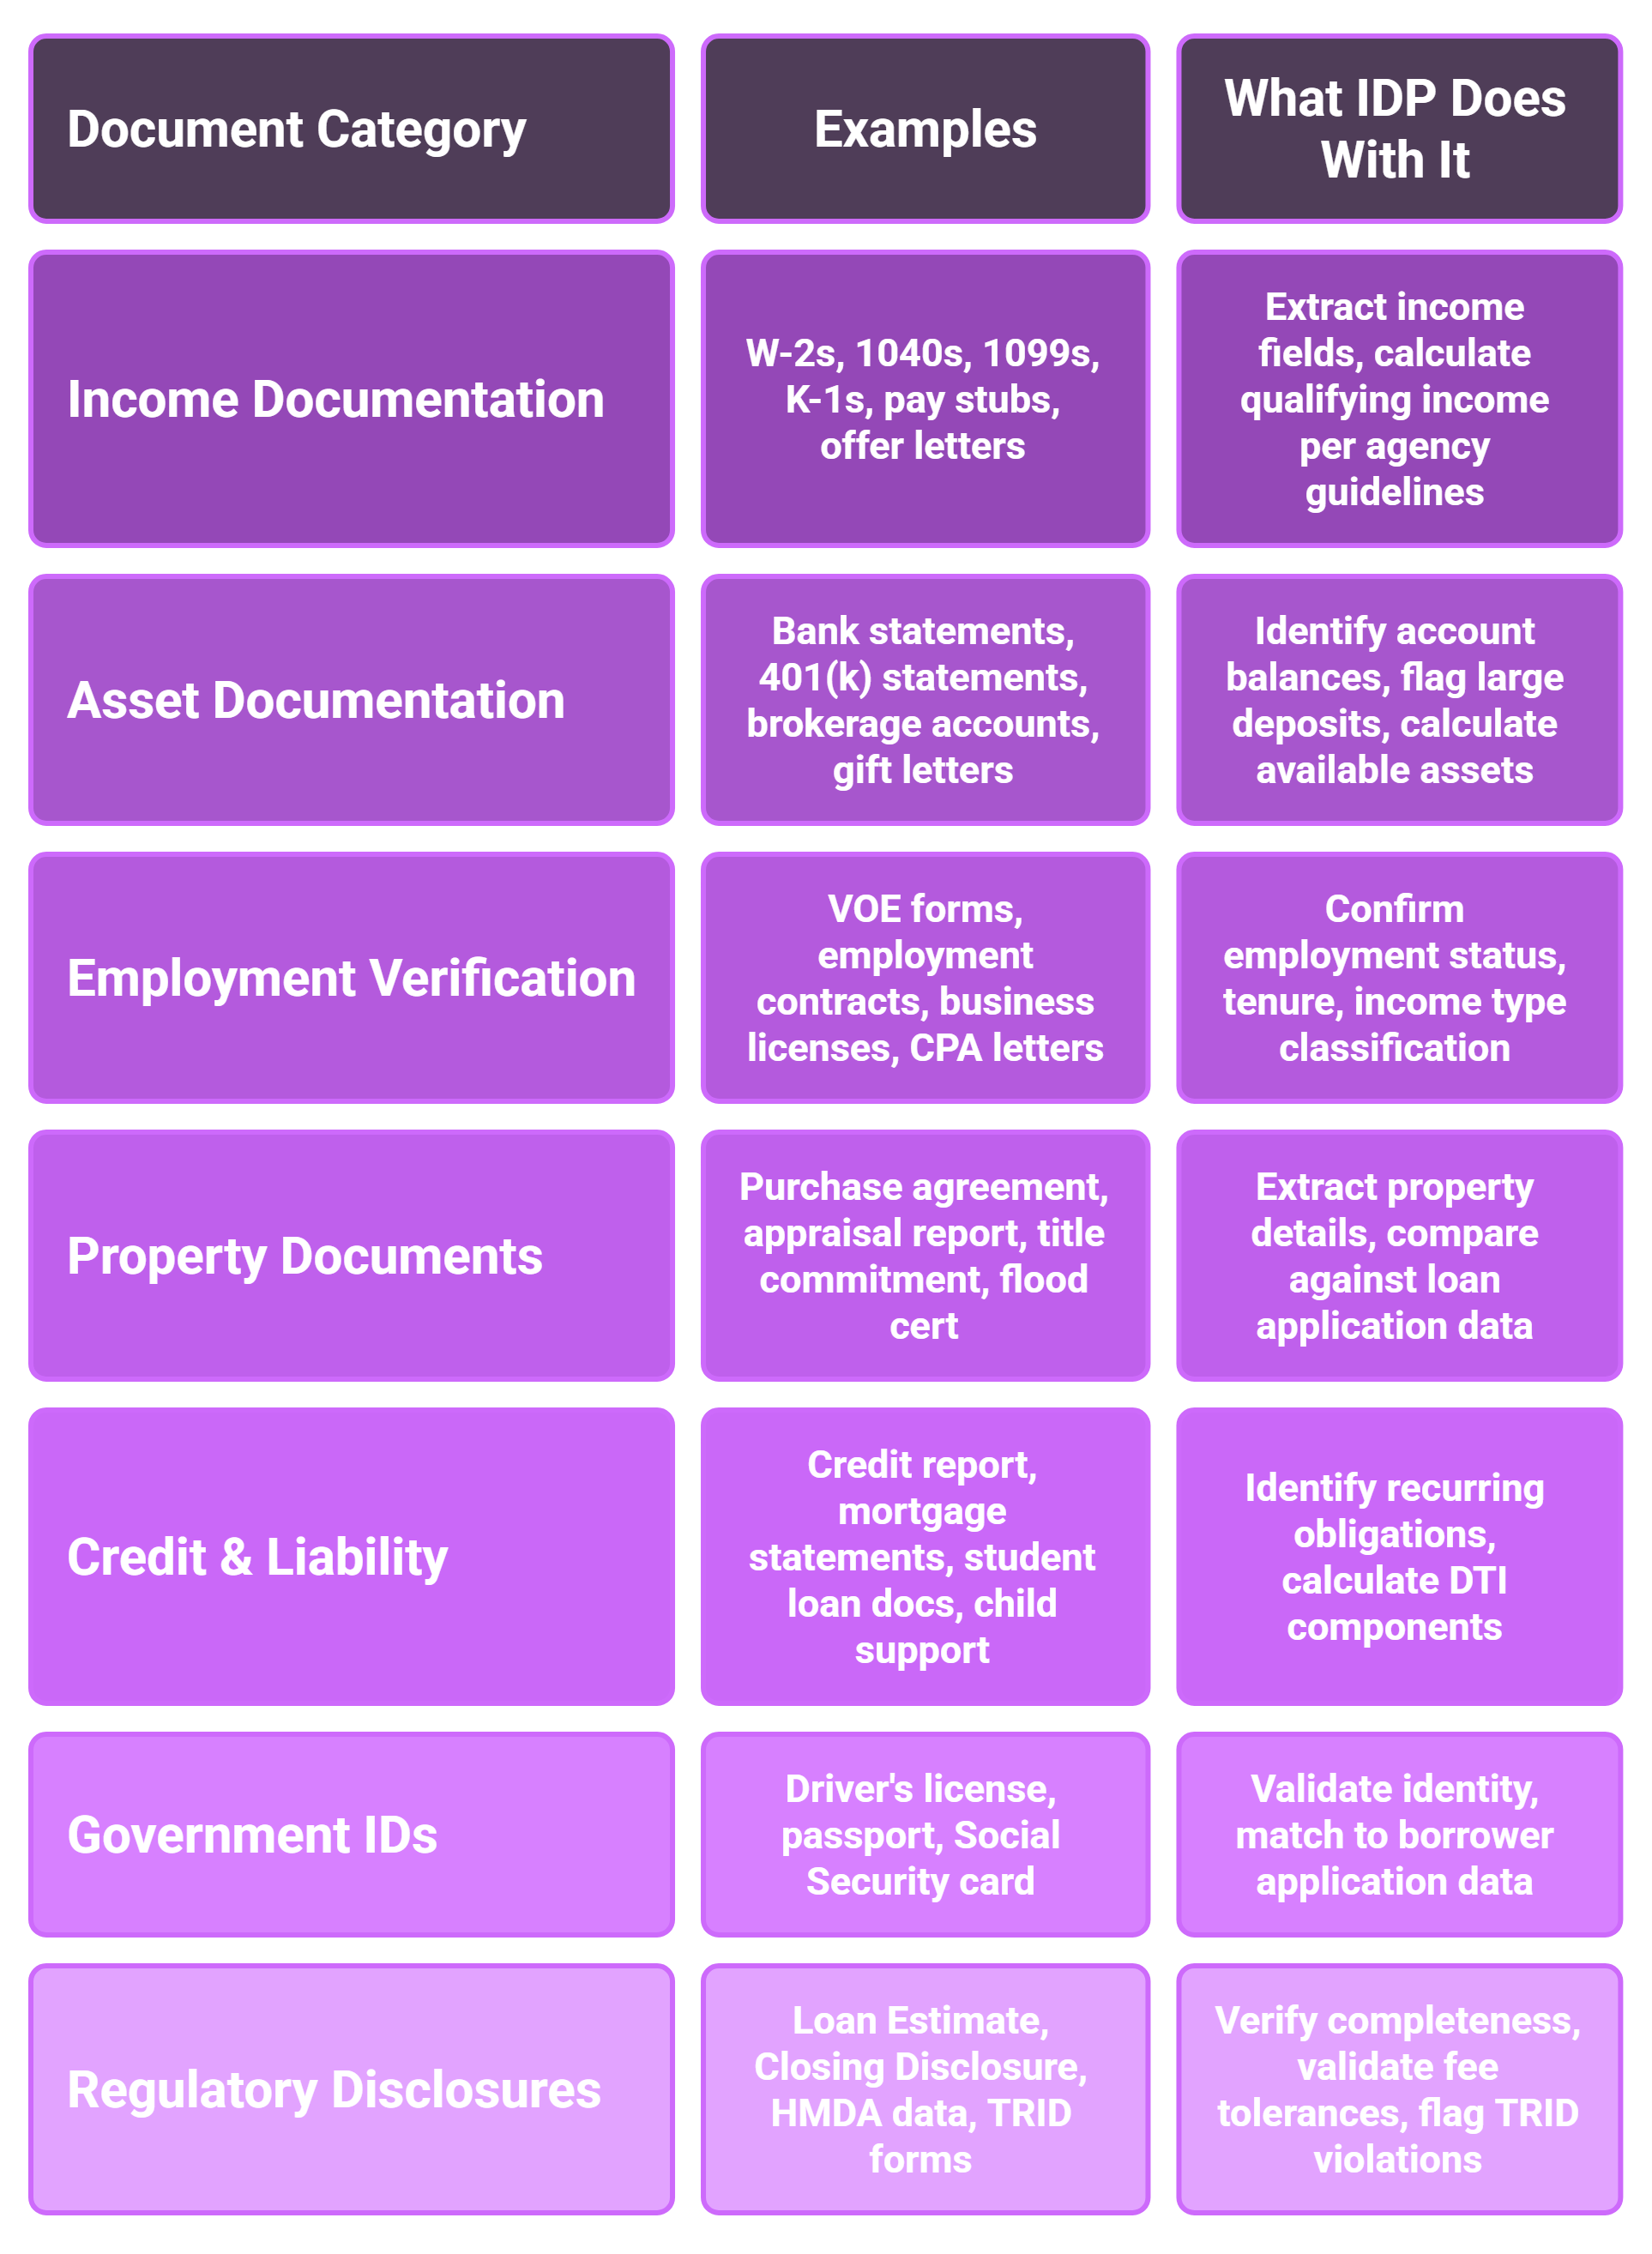
The table below covers the primary mortgage document categories, with examples of specific document types and a description of how IDP processes each one:
What IDP Means for Loan Officers Day-to-Day
For loan officers and processors who have spent years manually managing mortgage document workflows, IDP changes the nature of the job in ways that are both practical and significant:
From Document Chasing to Exception Management
With IDP, the system handles initial document receipt, classification, and completeness checking automatically. When a borrower uploads their documents, the IDP platform immediately identifies any missing items and can automatically notify the borrower through a configured communication workflow. The loan officer’s role shifts from chasing documents to reviewing the IDP exception report and managing the small percentage of cases that require human judgment.
Dramatically Faster Turnaround on Complex Income Scenarios
Self-employed borrowers, W-2 employees with substantial side income, and borrowers with complex asset structures have historically consumed disproportionate processor time. IDP handles complex income calculations — including two-year averaging for self-employed borrowers, business income normalization, rental income qualification, and depreciation add-backs — automatically, presenting the calculation with a complete audit trail that the underwriter can review and accept or override.
Audit-Ready Files from Day One
Every action the IDP system takes is logged: what was extracted, from which document, with what confidence level, and when. This creates a complete audit trail that satisfies both internal QC requirements and regulatory examination expectations. Loan officers who previously spent hours preparing files for compliance review find that AI-processed files are essentially audit-ready from the moment initial document processing is complete.
IDP and Mortgage Fraud Detection
A significant and often underappreciated benefit of IDP in mortgage processing is its role in identifying document manipulation and fraud indicators. Manual review catches obvious fraudulent documents only when a processor happens to notice an anomaly. IDP applies systematic checks that no manual reviewer can match:
- Metadata analysis: IDP can examine PDF metadata to identify documents that have been digitally altered, creation dates that do not match document dates, or editing software fingerprints inconsistent with an official document source.
- Pattern recognition: AI models trained on large volumes of legitimate tax forms, pay stubs, and bank statements can identify subtle formatting anomalies that indicate document manipulation — fonts that do not match authentic versions, number alignment inconsistencies, or field values that fall outside statistical norms for the document type.
- Cross-document consistency: IDP compares data points across documents and flags implausible combinations — an employer with unusually high listed wages, income that does not align with reported business revenue, or asset statements that show funding patterns inconsistent with reported income.
Mortgage fraud causes significant losses across the industry each year. IDP-powered fraud detection does not replace human judgment or fraud investigation teams, but it dramatically reduces the number of fraudulent applications that reach underwriting undetected.
Implementing IDP: What Mortgage Lenders Need to Know
LOS Integration
Modern IDP platforms for mortgage lending are designed to integrate with the leading Loan Origination Systems via secure API connections. Encompass, nCino, Byte, MortgageDirector, and most other major LOS platforms support API-based data intake. Implementation timelines for IDP-to-LOS integration typically range from four to eight weeks for standard integrations, depending on the complexity of custom data fields and workflow configurations.
Staff Training and Change Management
IDP adoption requires a meaningful change in how loan officers and processors interact with the file. Rather than working through documents manually, they work from the IDP exception report — reviewing flagged items, correcting high-priority extractions, and approving automated classifications. Most lenders find that processor teams adapt to exception-based workflows within two to four weeks, and that the response is strongly positive once the reduction in manual work volume becomes apparent.
Model Training and Customization
While leading IDP platforms arrive pre-trained on large mortgage document datasets, every lender has some unique document types, portfolio products, or state-specific forms that require additional model training. Quality IDP vendors provide supervised fine-tuning processes where your team can review and correct model outputs, with the model incorporating those corrections to improve accuracy on your specific document mix over time.
SimplAI Intelligent Document Processing for Mortgages
SimplAI’s IDP solution is purpose-built for mortgage lending, pre-trained on over 200 mortgage document types, and integrates via pre-built connectors with the leading LOS platforms. The platform includes real-time document validation, cross-document reconciliation, automated fraud indicator detection, and exception-based workflow management. Average accuracy on structured mortgage documents exceeds 99%, with a full audit trail on every extraction decision.
Conclusion: IDP Is the Foundation of the Modern Mortgage Operation
Every ambitious goal in mortgage operations — faster cycle times, lower origination costs, better borrower experiences, reduced fraud exposure — runs through document processing. As long as document handling is manual, the rest of the workflow is constrained by the pace and accuracy of human document review.
Intelligent Document Processing removes that constraint. By automating classification, extraction, validation, and LOS integration across all mortgage document types, IDP frees loan officers and processors to focus on the work that actually requires human judgment: complex income scenarios, risk assessment decisions, and borrower relationships.
For lenders evaluating AI adoption, IDP is not an advanced capability to plan for years from now. It is the foundational layer of any modern mortgage operation, and it is deployable in weeks, not years.
FAQs
What is intelligent document processing for mortgages
Intelligent Document Processing (IDP) for mortgages is an AI-powered technology that automates the ingestion, classification, data extraction, and validation of mortgage documents such as W-2s, tax returns, and bank statements. It integrates directly with Loan Origination Systems (LOS) to reduce manual work and improve accuracy.
How is IDP different from OCR in mortgage processing?
OCR converts scanned documents into machine-readable text, while IDP goes further by understanding document context, extracting structured and unstructured data, validating information, and learning from corrections. IDP is significantly more advanced and suitable for complex mortgage workflows.
What types of documents can IDP process in mortgage workflows?
IDP can process a wide range of mortgage documents including income documents (W-2s, 1099s), bank statements, tax returns, property documents, credit reports, government IDs, and regulatory disclosures.
How accurate is intelligent document processing for mortgages?
Modern IDP systems achieve 95–99% accuracy depending on document type. Structured documents like tax forms often exceed 99% accuracy, while unstructured documents achieve slightly lower but still high accuracy with AI validation.
How does IDP improve mortgage processing speed?
IDP reduces document processing time from 30–90 seconds per document (manual/OCR) to 2–5 seconds by automating classification, extraction, and validation. This significantly shortens loan cycle times
Author bio