The insurance industry does not have a shortage of artificial intelligence experiments.
Across underwriting, claims, fraud detection, distribution, and customer service, insurers have tested copilots, document-processing tools, predictive models, chatbots, and generative AI applications. Many of these projects produce a convincing demonstration. Far fewer become dependable, governed systems that employees can use every day.
That gap between an impressive pilot and a production-ready operation will be one of the most important conversations at ITC Vegas 2026.
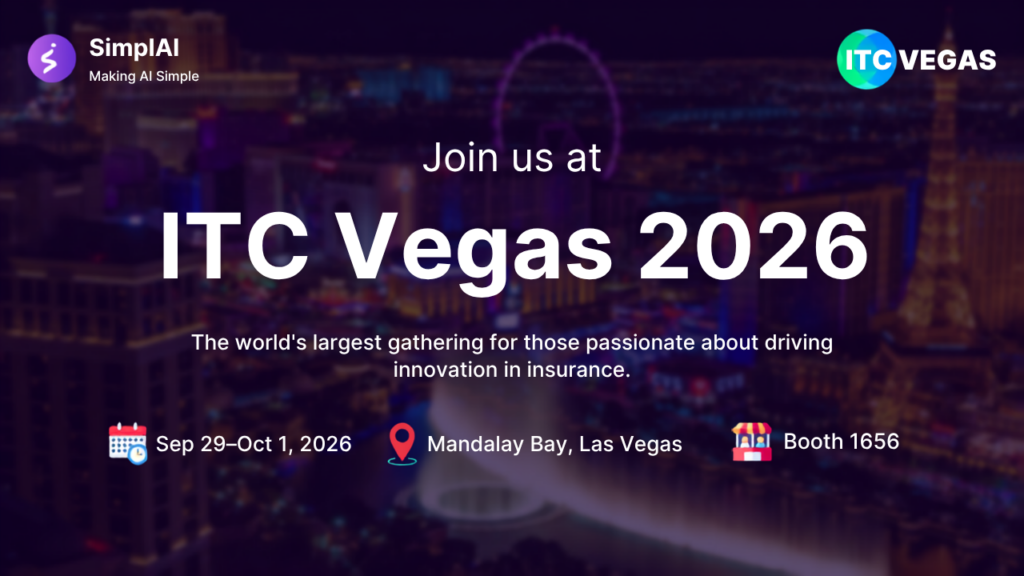
SimplAI will be part of that conversation at Booth 1656, demonstrating how insurers can build, deploy, orchestrate, and govern AI agents across complex workflows. Its presence comes as carriers, MGAs, brokers, reinsurers, and investors are asking a more mature question about enterprise AI.
The question is no longer simply, “What can an AI model do?”
It is: Can the organization trust it to operate inside a regulated insurance environment?
Taking place from September 29 to October 1, 2026, at Mandalay Bay in Las Vegas, ITC Vegas expects more than 9,000 attendees, 500 speakers, and 600 exhibitors. The event brings together insurers, reinsurers, technology providers, brokers, agents, entrepreneurs, and investors looking for practical solutions to the industry’s most persistent problems.
For attendees evaluating agentic AI for insurance, SimplAI Booth 1656 offers an opportunity to look beyond the model and examine the operating system required to move AI into production.
Why agentic AI matters to insurers in 2026
Traditional insurance automation is generally built around predefined steps: receive a document, extract specified fields, apply a rule, update a system, and refer exceptions to a person.
That approach remains useful. But insurance work is rarely as neat as the workflow diagram suggests.
A submission may contain inconsistent values across emails, PDFs, spreadsheets, and third-party databases. A claim can require policy verification, damage assessment, fraud screening, compliance checks, customer communication, and human approval. Underwriters regularly make decisions using context that cannot be reduced to a single static rule.
Agentic AI introduces a different operating model. An AI agent can be given an objective, access approved information and tools, execute multiple steps, evaluate the result, and route an exception to a human when necessary.
In insurance, that could mean an agent that:
- Receives a first notice of loss and identifies the relevant policy.
- Extracts and validates information from supporting documents.
- Checks whether required details are missing.
- Requests or recommends the next appropriate action.
- Screens the claim for inconsistencies or fraud indicators.
- Creates a structured summary for an adjuster.
- Records the evidence and reasoning behind each step.
The value is not merely faster text generation. It is the ability to coordinate work across documents, data sources, business rules, people, and existing systems.
That makes agentic AI potentially more valuable than another isolated assistant. It also makes governance, security, observability, and human control far more important.
Book a meeting with SimplAI at ITC Vegas 2026
The real obstacle is not model intelligence
AI models have become significantly more capable, but model capability alone does not make a system ready for insurance operations.
A proof of concept can often be assembled quickly because it works with limited data, cooperative test cases, and a controlled group of users. Production introduces harder questions:
- Which information is an agent allowed to access?
- What actions may it take without approval?
- How are sensitive policyholder records protected?
- Can every important decision be reconstructed?
- How are incorrect or low-confidence outputs handled?
- What happens when a connected service becomes unavailable?
- Can the insurer change models without rebuilding the workflow?
- How will the system comply with internal policies and regulatory obligations?
- Can it operate inside the insurer’s chosen infrastructure?
These are operating-system questions rather than prompt-engineering questions.
SimplAI positions itself as an enterprise Agentic AI Operating System designed to provide this surrounding layer. According to its platform materials, organizations can use SimplAI to create and coordinate specialized agents while managing access, deployment, evaluation, policy enforcement, and auditability centrally.
This distinction is likely to matter to ITC attendees. Insurers do not need a collection of disconnected AI demonstrations. They need a controlled way to turn selected demonstrations into reliable business capabilities.
What SimplAI is bringing to ITC Vegas 2026
SimplAI’s official ITC listing describes an enterprise agentic AI platform for underwriting, claims, customer service, fraud detection, and back-office operations. It emphasizes security, governance, observability, integration, and flexible deployment for regulated enterprises.
In practical terms, attendees visiting Booth 1656 should expect the conversation to center on four areas.
1. Insurance-specific AI agents
SimplAI presents agents for workflows including first notice of loss, fraud detection, underwriting, denial management, customer support, and Statement of Values processing.
These use cases share several characteristics: they are document-intensive, frequently repetitive, dependent on information spread across multiple systems, and consequential enough to require control.
Consider commercial underwriting. A Statement of Values may arrive in a spreadsheet containing incomplete addresses, inconsistent construction descriptions, duplicate locations, or badly formatted occupancy and protection data. Preparing that information can consume hours before an underwriter begins evaluating the actual risk.
An insurance AI agent can help clean, validate, and structure the submission, identify missing information, enrich approved fields, and prepare an audit-ready package. The goal is not to remove underwriting judgment. It is to stop using expensive underwriting time for avoidable data preparation.
The same principle applies to claims. An agent can assemble information, validate documents, summarize the file, and surface exceptions, allowing adjusters to concentrate on cases that genuinely require experience and empathy.
2. Multi-agent orchestration
A single agent will not always be sufficient for an end-to-end insurance process.
A claims workflow, for example, may need a document agent, policy-verification agent, fraud-detection agent, compliance agent, and communications agent. Those agents need to exchange context without receiving unrestricted access to every system or record.
SimplAI’s orchestration approach is intended to coordinate these specialized components inside one governed workflow. Each agent can have a defined responsibility, approved tools, access permissions, decision boundaries, and escalation conditions.
This is an important architectural shift. Instead of expecting one general model to perform every task, the organization can separate responsibilities and introduce controls at the points where risk is highest.
For insurers, this can also make the system easier to evaluate. A team can measure document extraction, fraud referral, policy verification, and customer communication separately instead of relying on one opaque measure of “AI accuracy.”
3. Governance and observability
The most interesting AI demonstration at a conference is not necessarily the one an insurer should purchase.
Buyers should pay close attention to what happens when the system is uncertain, wrong, or asked to act outside its authority.
SimplAI says its platform supports execution- and decision-level audit trails, role- and attribute-based access controls, environment isolation, evaluations, policy enforcement, and human approval points. These controls are intended to help an organization see what an agent did, which information it used, and why an action occurred.
That level of visibility is essential in insurance. A faster decision has limited value if the company cannot explain it to an internal reviewer, regulator, distribution partner, or policyholder.
Good governance should therefore be built into the workflow rather than added after the automation has been designed. Teams need to define permitted actions, escalation thresholds, retention rules, access policies, and human responsibilities before an agent is allowed to affect a live process.
4. Deployment flexibility
Insurance technology environments rarely follow a single architectural pattern. One carrier may prefer managed cloud services. Another may require a private cloud or virtual private cloud. A highly sensitive organization may need on-premises or isolated infrastructure.
SimplAI states that it supports cloud, private-cloud, on-premises, hybrid, and air-gapped deployment models. The platform also describes controls for data handling, retention, infrastructure ownership, and separation between development, staging, and production environments.
Deployment flexibility does not automatically guarantee compliance. Every insurer must conduct its own security, legal, privacy, model-risk, and procurement reviews. It can, however, remove an early architectural barrier when AI workloads must remain inside customer-controlled infrastructure.
High-value SimplAI use cases for insurers
ITC attendees will get more value from product discussions if they arrive with a specific operational problem rather than a general request to “use AI.”
Several insurance workflows are particularly suitable for evaluation.
First notice of loss and claims intake
FNOL is the beginning of the policyholder’s claims experience, but the required information may arrive through calls, emails, forms, photographs, and attached documents.
An AI agent can gather the initial details, identify the policy, classify the incident, detect missing information, create a structured record, and route the file to the appropriate team. This can reduce administrative effort while giving handlers a clearer starting point.
The insurer should still define which claims can proceed automatically, which require human review, and how vulnerable customers or ambiguous circumstances will be handled.
Underwriting submission preparation
Underwriters often spend substantial time reading emails, reviewing schedules, normalizing spreadsheets, checking documents, and re-entering information.
Agents can help convert unstructured submissions into consistent underwriting packages, compare values across documents, flag contradictions, and request missing data. In commercial lines, they may also assist with COPE-data preparation and Statement of Values validation.
The business case should be measured in more than elapsed time. Insurers should examine submission capacity, rework, data quality, referral frequency, quote turnaround, and the amount of underwriter attention redirected to risk selection.
Fraud detection and investigation
Fraud investigations require connections across claim histories, documents, entities, behavior, and external information. Static rules can catch familiar patterns but may generate excessive false positives or miss relationships spread across multiple data sources.
An agentic workflow can collect approved evidence, identify anomalies, connect relevant entities, and prepare an investigation narrative for human review.
The operative phrase is “for human review.” Fraud referrals can materially affect customers, so evidence, thresholds, bias testing, explainability, and appeal processes remain critical.
Customer service and policy servicing
Customer-service agents can assist with coverage questions, claim status, policy changes, renewals, billing inquiries, and document requests.
A production system should ground answers in approved policy and customer information instead of relying on the model’s general knowledge. It should also know when to stop, disclose its limitations, and transfer the interaction to a licensed or appropriately authorized person.
When designed well, an agent can shorten response times while preserving a clear route to human support.
Back-office and compliance operations
Insurance companies manage large volumes of reconciliations, bordereaux, regulatory documents, audit evidence, correspondence, and internal reporting.
These tasks may receive less attention than claims or underwriting, yet they can present attractive starting points for agentic automation. They are measurable, operationally expensive, and often have an existing human review process that can be retained during deployment.
What insurers should ask at Booth 1656
A conference demonstration should be the beginning of due diligence, not the end.
Insurers evaluating SimplAI or any agentic AI platform should ask questions that reveal how the technology behaves under real operating conditions:
- How does the platform ground outputs in our approved data?
Ask how sources are retrieved, prioritized, cited, updated, and restricted. - What prevents an agent from exceeding its authority?
Look for tool permissions, action limits, approval gates, policy enforcement, and role-based access. - Can we reconstruct an individual decision?
Ask to see the audit trail, model version, retrieved evidence, agent actions, human interventions, and final outcome. - How are low-confidence and exceptional cases handled?
A mature system should have escalation logic rather than treating every case as automatable. - How is performance evaluated after deployment?
Discuss accuracy, completion, exception, override, latency, cost, drift, and business-outcome metrics. - Which deployment models are available?
Confirm whether the platform supports the organization’s cloud, private infrastructure, residency, and network-isolation requirements. - How does SimplAI integrate with existing insurance systems?
Request a realistic discussion of core platforms, claims systems, data warehouses, CRMs, document repositories, APIs, and older technology. - What remains the insurer’s responsibility?
Clarify model-risk management, configuration, data quality, legal review, monitoring, human oversight, and incident response.
A useful vendor conversation is not one in which every answer is “fully autonomous.” It is one in which the boundaries of autonomy are precise and testable.
A practical route from ITC conversation to production
Insurers should resist two extremes: launching a company-wide transformation before the controls are ready, or running an endless pilot that never faces real operating conditions.
A better path starts with one valuable, bounded workflow.
Define the current baseline, including volume, handling time, error rate, rework, cost, customer impact, and compliance requirements. Identify the decisions an agent may make, the decisions requiring human approval, and the conditions that should stop the workflow.
Then test the system using representative cases—not only clean examples. Include incomplete submissions, conflicting documents, unusual policies, unavailable integrations, ambiguous instructions, and adversarial inputs.
A production decision should evaluate at least four dimensions:
- Business value: Does the workflow improve a meaningful operating outcome?
- Quality: Are outputs sufficiently accurate and consistent?
- Control: Can the company explain, restrict, and reverse agent actions?
- Adoption: Can employees realistically incorporate the system into their work?
Only after these conditions are met should the organization expand into additional products, teams, or agent responsibilities.
Why SimplAI’s ITC Vegas 2026 presence matters
Insurance AI is entering a more demanding phase.
The excitement around generative AI has created awareness, experimentation, and executive sponsorship. Now insurers must determine which platforms can survive contact with real data, legacy systems, regulatory obligations, operational exceptions, and customers who expect fair treatment.
SimplAI’s proposition is that enterprises need an operating system around AI agents: one place to build them, connect them, govern them, observe them, and deploy them within the organization’s chosen infrastructure.
ITC Vegas 2026 gives insurers and investors a valuable setting in which to test that proposition.
The most productive conversation at Booth 1656 will not begin with, “Show me everything AI can automate.” It will begin with a specific workflow, a measurable business problem, and a clear statement of the controls that cannot be compromised.
That is how the insurance industry can move from AI theatre to operational value.
Meet SimplAI at ITC Vegas 2026
Visit SimplAI at Booth 1656 during ITC Vegas 2026 at Mandalay Bay, Las Vegas, from September 29 to October 1.
Bring a workflow that is slow, fragmented, document-heavy, or difficult to scale. The SimplAI team can discuss how governed AI agents could support the process, where human oversight should remain, and what would be required to move from initial evaluation to production.
Book a meeting with SimplAI at ITC Vegas 2026
Frequently asked questions
Where can I find SimplAI at ITC Vegas 2026?
SimplAI is listed at Booth 1656. ITC Vegas 2026 takes place at Mandalay Bay in Las Vegas from September 29 to October 1, 2026.
What does SimplAI do for insurance companies?
SimplAI provides an enterprise platform for building, orchestrating, deploying, and governing AI agents. Its insurance use cases include underwriting, FNOL, claims processing, fraud detection, customer support, denial management, and back-office automation.
What is agentic AI in insurance?
Agentic AI refers to systems that can pursue a defined objective, use approved tools and data, complete multiple workflow steps, and escalate decisions when necessary. Unlike a basic chatbot, an AI agent can assist with operational execution under configured controls.
Can SimplAI be deployed on premises?
SimplAI says its platform supports cloud, private-cloud, on-premises, hybrid, and air-gapped deployments. Availability and suitability should be confirmed during technical and security due diligence.
Does agentic AI replace insurance professionals?
The more credible near-term use is to support professionals by handling repetitive information gathering, validation, summarization, and workflow coordination. Insurers should retain human review for consequential, ambiguous, exceptional, or legally restricted decisions.
How should an insurer begin evaluating SimplAI?
Start with a bounded, high-volume workflow with measurable costs and an existing human review process. Establish the baseline, decision boundaries, escalation rules, security requirements, and success metrics before beginning a pilot.
Author bio